Solicited Corporate Credit Rating for CESARE ATTOLINI S.P.A.: A2- (Affirm)
modefinance published the Solicited Corporate Credit Rating of CESARE ATTOLINI SPA on the website and the rating assigned to the entity is A2- (Affirm). The analysis revealed that the Company demonstrates an outstanding ability to fulfill its obligations.
CESARE ATTOLINI S.P.A., whose origins date back to the 1930s, is today internationally renowned as an excellence in Neapolitan tailoring and men’s elegance. The brand stands out for its selection of the finest materials, meticulous craftsmanship, and the exclusivity of its garments, elements that make it an icon of luxury menswear worldwide. Under the leadership of Massimiliano and Giuseppe Attolini, Cesare’s sons, the Company is strengthening its international vocation, expanding the brand’s presence through strategic boutiques and single-brand stores, and enhancing Cesare Attolini’s prestige as an authentic symbol of Italian style and tailoring.
Key Rating Assumptions
CESARE ATTOLINI S.P.A. confirmed its solid financial profile in 2025, further strengthened by the continued increase in shareholders’ equity and the achievement of a net cash position. Shareholders’ equity rose to €18.93 million, supporting the enhancement of solvency indicators and confirming the Company’s limited reliance on external funding. Despite an increase in gross financial debt aimed at supporting growth and international expansion initiatives, the significant increase in cash and cash equivalents enabled the Company to close the year with a positive net financial position of approximately €0.69 million. Sales revenues increased to €19.01 million in 2025 (+7.5% compared with 2024), supported by stronger demand in established markets and by the growing contribution of international commercial initiatives. Despite higher personnel expenses and operating costs incurred to support business growth, the Company maintained strong profitability levels, with EBITDA amounting to €4.62 million and EBIT reaching €4.21 million. The year ended with a net profit of €2.95 million, while profitability indicators remained at very satisfactory levels, with ROI and ROE standing at 16.3% and 15.6%, respectively.
In terms of cash flow generation, the Company continued to demonstrate a solid self-financing capacity which, together with the recovery of financial resources deployed within subsidiaries and the partial disposal of financial investments, supported the increase in available liquidity to €5.52 million.
CESARE ATTOLINI S.P.A. has a solid governance and control structure: management is entrusted to a properly composed Board of Directors, while control and statutory audit functions have been delegated to a Board of Statutory Auditors and a leading auditing firm, respectively. The Company, directly controlled by Mr. Giuseppe Attolini (50%) and Mr. Massimiliano Attolini (50%), heads a group of companies that actively contribute to business development in Italy and abroad. No adverse findings have been identified concerning the directors, shareholders, or the Company itself.
Compared to its peer group, the Company demonstrates an adequate size positioning, ranking among the largest operators in the sample. Solvency and profitability metrics are also strong, well above the respective median reference values. On average, companies in the peer group show adequate capitalization and balanced financial leverage; profitability has recovered, returning to satisfactory levels.
The international macroeconomic environment continues to be characterized by moderate growth and a high degree of uncertainty. Forecasts for 2026 point to GDP growth of 1.1% in the European Union, 0.9% in the Eurozone and 3.0% globally. Economic prospects remain influenced by geopolitical tensions, developments in energy markets and international trade policies. In the United States, the Federal Reserve continues to adopt a prudent monetary policy stance, within a scenario that still envisages positive economic growth over the 2026-2027 period
Sensitivity Analysis
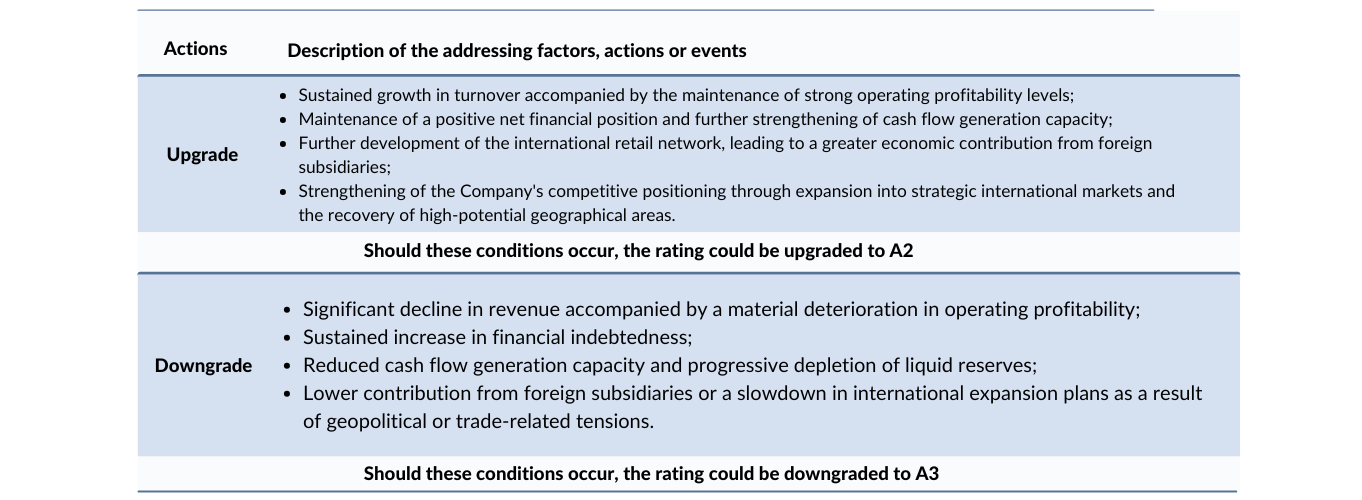
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated company has not purchased ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com