Solicited Corporate Credit Rating for PASOLINI LUIGI S.R.L: B1 (Affirm)
modefinance published the Solicited Corporate Credit Rating of PASOLINI LUIGI S.R.L. on the website and the rating assigned to the entity is B1 (Affirm). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
PASOLINI LUIGI S.R.L. (hereinafter also referred to as "the Company"), founded in 1959 and headquartered in Castel Mella (Brescia), has evolved from a company specialized in visual communication and retail fit-out solutions into a general contractor providing turnkey design, construction and project management services for the large-scale retail trade (GDO), retail, and industrial sectors. Over recent years, the Company has strengthened its market positioning through the expansion of its general contracting activities, investments in its operational and logistics infrastructure, and the opening of a commercial office in Milan. The “Pasolini” brand, officially recognized in 2024 as a Historic Trademark of National Interest, reflects the Company's long-standing heritage and established market presence. At the same time, participation in the ELITE programme, together with an increasing focus on corporate governance and sustainability initiatives, supports its ongoing development and growth strategy. Leveraging a portfolio of more than 500 active customers and long-standing relationships with leading national and international brands, the Company is currently positioned among the leading independent Italian operators in the commercial fit-out and retail contracting sector.
Key Rating Assumptions
PASOLINI LUIGI S.R.L. displays an overall satisfactory economic and financial profile. In 2025, the Company continued to report revenue growth, while maintaining stable operating margins and profitability indicators, which remained at more than adequate levels. From a financial standpoint, the Company preserved an appropriate balance between short-term sources and uses of funds, although its working capital cycle continues to require close monitoring.
The capital structure was further strengthened by the increase in shareholders’ equity, while total liabilities remained broadly stable, resulting in a reduction in leverage levels. Net Financial Position (NFP), although higher than in 2024 due to the increase in financial indebtedness, remains consistent with the Company’s equity base. Furthermore, debt sustainability remains at adequate levels in relation to the operating profitability generated by the core business.
PASOLINI LUIGI S.R.L. has a straightforward and transparent ownership structure, with shareholdings held by Giacomo Pasolini (40%), Pierpaolo Pasolini (40%), and Athena Financial Advisory S.r.l. (20%). The Company is governed by a collegiate Board of Directors, supported by a sole statutory auditor acting as the supervisory body. The Company has also implemented an Organizational, Management and Control Model pursuant to Italian Legislative Decree 231/2001, aimed at preventing risks associated with corporate administrative liability and strengthening internal control procedures across its business processes. No adverse findings were identified with respect to the Company, its shareholders, or the members of the governing bodies.
From a macroeconomic perspective, Italy's economy continued to expand at a moderate pace during the first months of 2026, driven primarily by the services sector, while manufacturing activity remained under pressure due to higher energy costs and weak external demand. Household consumption and private investment recorded only modest growth as a result of persistent uncertainty and reduced purchasing power. According to the latest projections of the Bank of Italy, real GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. Nevertheless, the outlook remains subject to significant downside risks associated with geopolitical developments, energy commodity prices, and international trade conditions.
Sensitivity Analysis
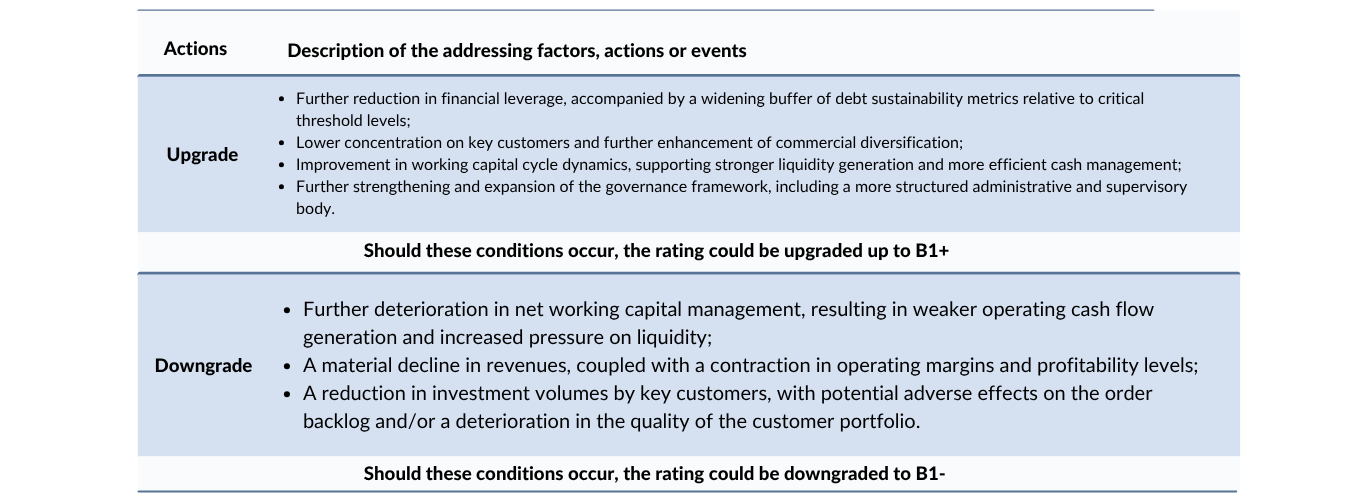
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company did not purchased any ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Azzurra Nicchi, Rating Analyst
azzurra.nicchi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com