Solicited Corporate Credit Rating for TOP ENERGY S.R.L.: B1- (Affirm)
modefinance published the Solicited Corporate Credit Rating of TOP ENERGY S.R.L. on the website and the rating assigned to the entity is B1- (Affirm). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
TOP ENERGY SRL (hereinafter also referred to as “the Company”), founded in Naples in 2018, operates in the supply of natural gas and electricity. The Company currently serves 5,000 active accounts and aims to reach 8,000 customers by the end of 2026. Its existing customer portfolio is primarily concentrated in Campania, Piedmont, and Lombardy, with planned expansion into Calabria, Apulia, and Tuscany. The company currently offers variable pricing linked to market trends and plans to introduce fixed-price products starting in 2026. TOP ENERGY SRL has strengthened its positioning within the energy value chain, becoming both a trader and a direct supplier, with a focus on sustainable growth. Its strategy is based on strengthening its nationwide presence and ensuring accurate metering-data management to deliver transparency and competitive pricing. The 2026–2028 Business Plan outlines a growth trajectory driven by the expansion of electricity and natural gas sales, with a progressive increase in both the value of production and EBITDA. The forecasts point to stronger financial performance and enhanced earnings-generation capacity.
Key Rating Assumptions
TOP ENERGY S.r.l. closed 2025 with a solid and improving financial profile. Revenue increased by 11.87% to €7.81 million, while net profit reached €583 thousand, up 14.54%, with operating margins remaining broadly stable. The company’s capital structure strengthened as shareholders’ equity rose by 24.27% to €1.70 million, reducing leverage from 2.11x to 1.70x. Financial debt remained marginal and fully sustainable, with a positive net financial position of €509 thousand. Liquidity also improved, with the current ratio rising from 1.44x to 1.66x, supported by higher current assets and lower short-term liabilities. ROI (18.09%) and ROE (34.27%) remained strong, confirming the Company’s solid overall profitability.
The Company has a clearly identifiable ownership structure. Its majority shareholder is ISNE S.R.L., which is itself wholly owned by Giovanni Nenna, the Sole Director of the Company. A statutory auditor was appointed in 2026. No adverse findings have been identified in relation to the shareholders, the members of the governing body, or the Company itself. In terms of revenue, compared with its peer group, the Company’s positioning is not entirely satisfactory. However, its solvency and profitability metrics outperform the respective peer group medians.
Between late 2025 and 2026, the energy market has been characterised by growing electricity demand and the rapid expansion of renewable energy, particularly solar photovoltaic and wind power. However, fossil fuels continue to play a central role, while geopolitical tensions in Iran and restrictions affecting the Strait of Hormuz are increasing energy-price volatility and inflationary pressures. In Italy, renewable sources account for 41% of electricity consumption. Nevertheless, the country’s continued reliance on natural gas is keeping energy prices elevated and has prompted the Government to postpone the closure of certain coal-fired power plants in order to safeguard energy security.
From a macroeconomic perspective, the Italian economy recorded weak growth in the first quarter of 2026, driven primarily by the services sector. Manufacturing, household consumption, and investment were adversely affected by rising energy costs and international uncertainty. The Bank of Italy forecasts GDP growth of 0.5% in both 2026 and 2027, followed by 0.8% in 2028.
Sensitivity Analysis
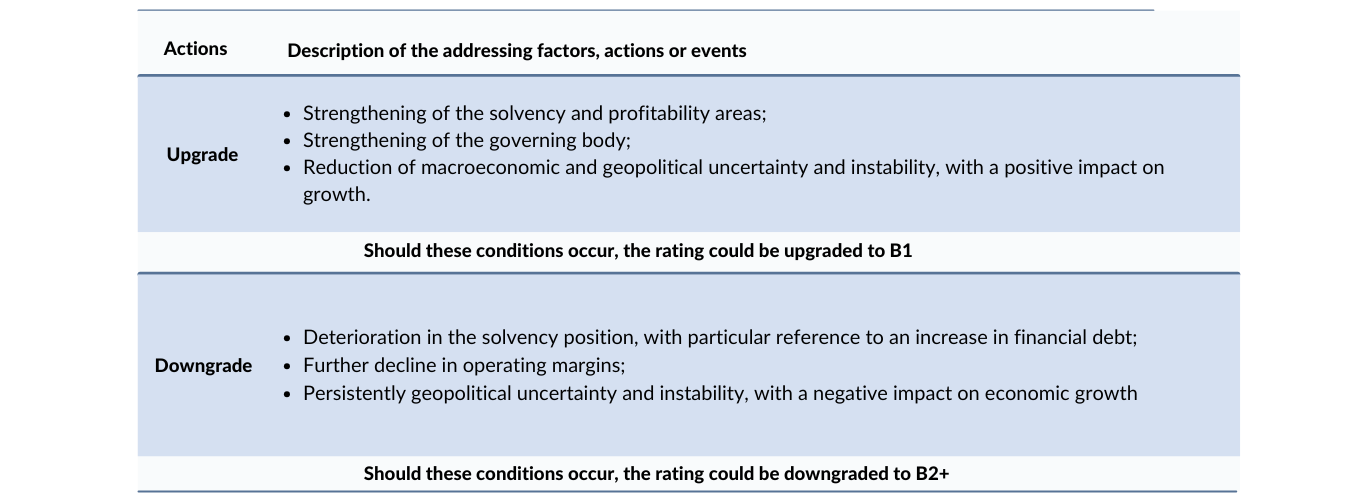
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company purchased ancillary services from modefinance (preliminary rating). Modefinance guarantees that this purchase of ancillary activities does not constitute any conflict of interest.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the people reported above, modefinance Ratings will provide the appropriate information and if necessary, the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity and should be relied upon to a limited degree. The issued rating is subject to ongoing monitoring until withdrawal.
Contacts
Head Analyst - Mattia Dunnhofer, Rating Analyst
mattia.dunnhofer@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com