Solicited Corporate Credit Rating for BORA S.P.A.: B1 (Affirm)
modefinance published the Solicited Corporate Credit Rating of BORA S.P.A. on the website and the rating assigned to the entity is B1 (Affirm). The analysis highlights that the company has an adequate economic and financial situation, demonstrating an average capability to meet its financial obligations and remaining minimally affected by adverse economic scenarios.
BORA S.P.A. was founded in 1975 by Elio Bora, initially specializing in the design and manufacture of moulds and components for the household appliance market. Over the years, the Company diversified into the automotive industry, which offers higher profit margins and has become its core business, accounting for approximately 60% of turnover in fiscal year 2025. BORA operates production facilities in Italy and Poland, serving Europe - particularly Italy, France, Spain, Great Britain, Germany, Poland, Slovakia, and the Czech Republic - and generates a smaller portion of revenue from international markets such as Turkey and Mexico. Following the increase in production costs, the management updated sales price lists during 2024. Until then, these lists were adjusted automatically only in line with raw material prices (primarily steel).
Key Rating Assumptions
In 2025, BORA S.P.A. (the “Company”) reported substantially stable Value of Production of EUR 37.3 million (+1% vs. 2024), despite an uncertain market environment. Gross operating margin stood at EUR 2.5 million, or around 7%, thanks to the re-pricing initiatives launched during 2024. Before provisions for risk funds of EUR 0.55 million, MOL would have amounted to EUR 3.1 million (+22% YoY), and the MOL margin would have been 8.3% (+1.5 p.p. YoY). Net income improved to EUR 0.8 million, and ROE rose to 7.7%, benefiting from the reduction in bank debt. Despite the buy-back following the other shareholder's exit, net equity remained solid at EUR 11.0 million as at June 2026 (EUR 10.7 million at December 2025 and 2024). NFP fell from EUR 4.6 million at December 2024 to EUR 1.0 million at December 2025 and further declined to EUR 0.5 million at June 2026. Although the automotive industry's uncertain regulatory and technological phase will negatively impact 2026 revenues, the management cost-saving initiatives will mitigate the expected decline in revenues and operating margins. In light of these factors, the Agency believes that the Company will achieve an NFP/MOL ratio below 1.0x in December 2026. Between December 2024 and December 2025, cash and cash equivalents increased from EUR 6.8 million to EUR 7.7 million, supported by net operating cash flow and largely driven by the reduction in trade receivables from EUR 8.6 million to EUR 5.6 million. Cash remained substantially stable at EUR 7.6 million as at June 2026 (EUR 0.1 million lower than at December 2025). Cumulative net operating cash flow generated between January 2025 and June 2026 financed a large part of bank loan repayments, which were only partly financed through new borrowings. To a limited extent, the cash generated funded the investments in fixed assets and the purchase of treasury shares.
The Company has a Board of Directors composed of two members: Cristiano Bora, serving as Chairman, Chief Executive Officer and shareholder, and Valerio Fedeli. Additionally, six authorized signatories hold specific powers, including Lorenzo Buldrini, appointed CFO in 2024. Bora S.p.A. has a collegial supervisory body and has also appointed an external professional to carry out monitoring activities pursuant to Legislative Decree 231/2001. The statutory audit of the financial statements is entrusted to a specialized auditing firm. In 2006, the Polish subsidiary Bora Poland Sp. z o.o. was established - a manufacturing company that, on behalf of Bora S.p.A., performs processing activities related to the household appliance market. BORA achieved the highest Legal Rating (3 stars) awarded by the Italian Competition Authority (AGCM); since 2021, the Company has been publishing its Sustainability and ESG Report and in 2025 was honored with the Sustainability Award by Kon Group, being ranked among the top 100 Italian companies for ESG performance.
BORA S.p.A. has a large size profile, with total revenues over EUR 37 million in 2025. Although positioned below the sector median, the Company shows an overall adequate solvency profile. Between December 2024 and June 2026, financial leverage and NFP substantially improved. The Company’s profitability is above the sector level, confirming sufficient levels in 2025. The reference peer group shows an overall sufficient economic and financial standing, with an adequate balance between equity and debt, a balanced sources-and-uses structure, and contained profitability, which in 2025 shows a slight recovery after three years of contraction.
The ECB’s macroeconomic projections published in March 2026 indicate that euro area headline inflation is expected to rise to 2.6% in 2026, mainly driven by higher energy prices linked to the war in the Middle East, before easing to 2.0% in 2027 and 2.1% in 2028. Disruptions in commodity markets are weighing on real incomes and confidence, negatively affecting consumption and investment. In particular, annual real GDP growth is expected at 0.9%, 0.3 percentage points lower than in the previous December projections, while growth for 2027 and 2028 is estimated at 1.3% and 1.4%, respectively. Over the medium term, domestic demand will remain the main driver of growth, supported by a stable labour market, planned public spending on defense and infrastructure, and the continuation of digitalization and the AI-driven investment cycle. On the external side, structural competitiveness challenges will result in a persistent loss of market share for the euro area. The current energy crisis underscores the need for a green transition to reduce dependence on fossil fuels. Strengthening competitiveness and financial integration in Europe will also require the prompt regulation and adoption of the digital euro.
The European automotive sector has not yet recovered to pre-pandemic production levels and faces intense competitive pressure. In the first half of 2026, new car registrations in the European Union grew by 5.7% to 5.90 million units. ANFIA expects full-year volumes of slightly above 10.80 million units (+0.5%), with a slowdown in the second half. Leading Chinese groups reached a 9.3% share of the EU market in the first half of 2026. Chinese car exports rose from around 5 million to nearly 10 million units over recent years, making China the world’s leading car exporter since 2023. In Italy, new car registrations reached 0.94 million units in the first half of 2026, up 9.5% on the same period of 2025 and above the European average. Domestic vehicle production stood at approximately 0.30 million units in the half-year (+13.4%), driven by passenger cars, with 0.17 million units (+26.1%). Output nonetheless remains well below the potential capacity of the five major Italian plants, which ANFIA indicates at around 250,000 vehicles each. In Italy, electrification remains behind the main European markets: in June, battery electric vehicles (BEVs) accounted for 10.2% of national registrations, compared with 28.4% in Germany. The sector’s main risks are the competition from Chinese manufacturers and the ongoing revision of the CO₂ Regulation. German carmakers’ difficulties are transmitted to the Italian supply chain via component exports. Germany is the primary destination market for Italian parts and components producers; in the first five months of 2026, Italian automotive component exports to Germany fell by 4.6% compared with the same period of 2025.
Sensitivity Analysis
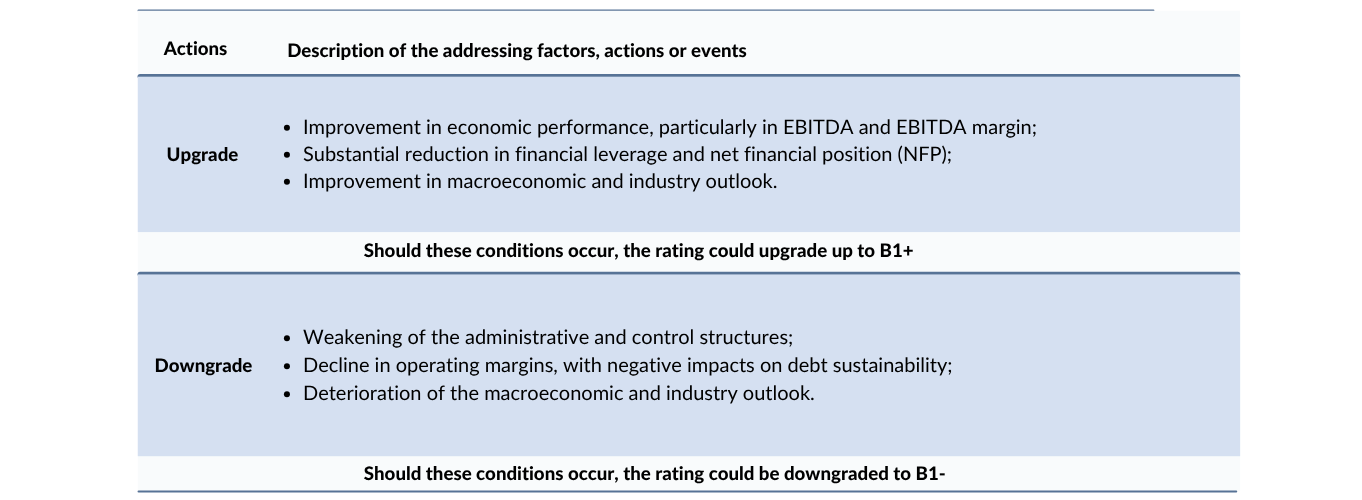
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
Some amendments were applied to the content of the credit rating report(s) or press release(s) after the notification process. The rated entity is not a buyer of ancillary services provided by modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Carmela Santomarco, Rating Analyst
carmela.santomarco@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com