Solicited Corporate Credit Rating for BORGOSESIA S.P.A.: A3- (Affirm)
modefinance published the Solicited Corporate Credit Rating of BORGOSESIA S.P.A. on the website and the rating assigned to the entity is A3- (Affirm). The analysis indicates that the company has an adequate ability to meet its obligations, though it remains somewhat exposed to adverse economic conditions.
BORGOSESIA S.P.A. (hereinafter also referred to as “the Company”), operates in the investment sector, specializing in both proprietary investments and the management of investment activities on behalf of third-party investors. Founded in 1873 as a textile and wool industry operator, the Company has undergone several ownership changes over the decades. BORGOSESIA conducts its business through its subsidiaries, primarily operating in the real estate sector with a focus on property investments, as well as in the alternative finance segment, where activities are mainly centred on securities and financial investments. In 2026, the Group progressively reshaped its operating model towards the acquisition and management of credit exposures, reducing its reliance on the direct acquisition of real estate assets underlying mortgage guarantees, while simultaneously strengthening its presence in the areas of alternative finance, bridge financing and corporate restructuring transactions. The Company is listed on the Italian Stock Exchange's Electronic Equity Market (Euronext Milan).
Key Rating Assumptions
The BORGOSESIA Group continues to demonstrate an overall balanced economic and financial profile. Solvency metrics remain broadly adequate, with a leverage ratio = 2.96x, despite a moderate increase compared with the previous period. The capital structure remains sound and supportive of the Group's operations. During 2025, the Company continued its bond issuance programme, resulting in a higher debt position and an increase in net financial debt from approximately €115 million to €151 million. Despite the growth in turnover compared with 2024 (€30 million versus €21 million), net profit recorded a slight decline, decreasing from €4.0 million to €3.2 million. This reduction was primarily attributable to financial management factors, namely higher interest expenses associated with increased indebtedness and lower financial income compared with the previous year. Overall, operating and financial performance remain adequate.
The Company maintains a governance and control framework aligned with best practice endorsed by CONSOB, supported by a corporate structure that is both articulated and clearly defined in terms of roles and responsibilities. The public tender offer completed in August 2026 led to a significant concentration of BORGOSESIA S.P.A.'s ownership structure without affecting the Group's corporate perimeter or operating activities. Prior to the transaction, the share capital was distributed among several significant shareholders and a free float of 45.32%. Following the transaction, Alba S.r.l. acquired a controlling stake representing 79% of the share capital, while the free float decreased to 21%. Furthermore, Istituto Atesino di Sviluppo S.p.A. continues to hold a 40% interest in Alba S.r.l.
Compared with the reference peer group, Borgosesia demonstrates a scale and profitability profile broadly in line with industry averages, although profitability declined during 2025. Solvency metrics remain below the sector median; however, on a stand-alone basis, the Company continues to exhibit a balanced financial and capital structure. The sector peer group as a whole maintains a sound capital and financial profile, showing slight improvement over the period under review. Financial leverage remains at balanced levels, while liquidity management appears robust, with adequate coverage of short-term obligations. From a profitability perspective, Return on Equity (ROE) has remained broadly stable at satisfactory levels, whereas Return on Capital Employed (ROCE) has shown greater volatility and a decline in the most recent financial year.The Italian economy continued to expand at a moderate pace during the first months of 2026, against a backdrop of heightened geopolitical uncertainty. Economic activity was primarily supported by the services sector, also benefiting from the temporary boost generated by the Winter Olympic Games, while manufacturing showed signs of weakness due to rising energy costs and subdued external demand.
Household consumption increased moderately, constrained by weakening consumer confidence and the erosion of purchasing power caused by higher energy prices. Investment activity also slowed, with positive contributions limited by macroeconomic uncertainty and the gradual reduction of incentives within the residential real estate sector. According to the latest projections from the Bank of Italy, Italian GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. Over the medium term, economic activity is expected to benefit from easing inflationary pressures and a recovery in domestic demand. In the short term, however, downside risks remain linked to developments in the Middle East conflict, fluctuations in energy commodity prices and uncertainties affecting international trade
Sensitivity Analysis
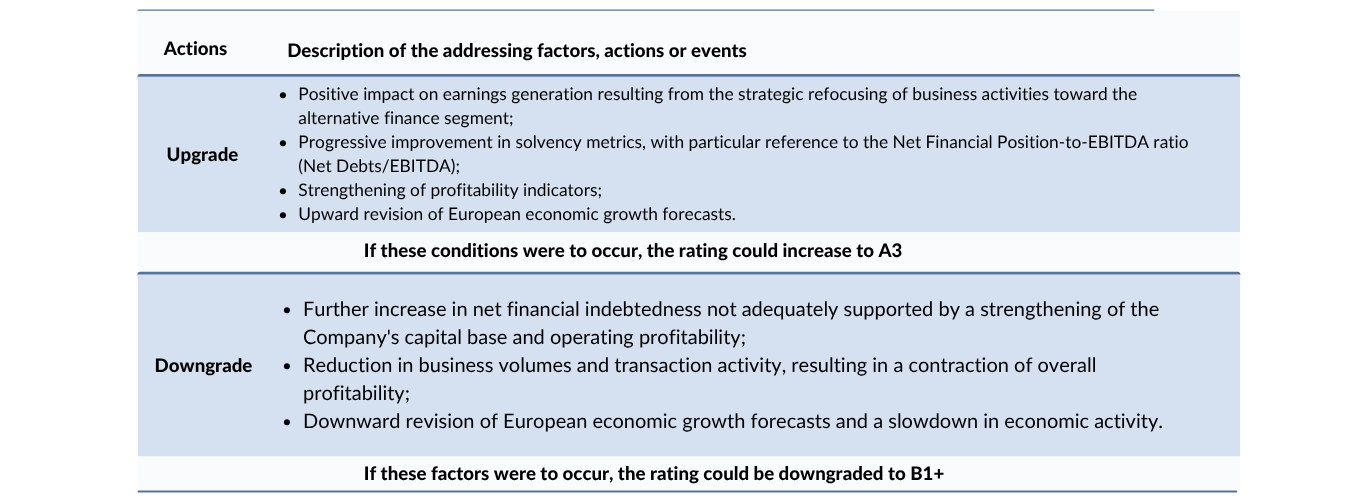
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated entity is not a buyer of ancillary services provided by modefinance
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com