Solicited Corporate Credit Rating for DO IT NOW S.P.A.: B1 (Affirm)
Modefinance published the Solicited Corporate Credit Rating of DO IT NOW S.P.A. on the website and the rating assigned to the entity is B1 (Affirm). The analysis shows that the rating of the Company is investment grade, which shows an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
DO IT NOW S.P.A. (hereinafter also referred to as “the Company” or "the Group") is a digital technology hub operating through its operating subsidiaries, in particular Supermoney and Massima Energia, which contribute substantially to consolidated revenues. Supermoney is the leading Italian digital marketplace for utilities, while Massima Energia, established in 2021, is an electricity and gas supplier aiming to develop Italy’s first “triple offer” (electricity and gas, mobile, fiber), integrating online and offline channels.
Key Rating Assumptions
Overall, DO IT NOW confirms an adequate economic and financial condition, characterized by a balanced capital structure (leverage ratio = 1.30x) and a level of net financial debt (EUR 8.66 million) which, although increasing, remains sufficiently sustainable (NFP/EBITDA = 2.54x). The management of current assets and liabilities is also sound (current ratio = 2.57x), as is the balance of cash flow dynamics. In 2025, the Group recorded an increase in cash and cash equivalents. Positive operating performance was confirmed, supported by self-financing and by net working capital dynamics, which were affected by the increase in trade receivables. However, operating cash generation was not sufficient to cover investments, which were entirely allocated to intangible assets and related to technological and commercial development. New financing was therefore required through the drawdown of bank debt. In terms of profitability, the Group, also owing to unfavorable market dynamics, recorded a decline in revenues (EUR 35.29 million; -35%) and margins (EBITDA = EUR 3.41 million vs EUR 8.53 million), closing the year with a net loss (EUR 2.85 million).
DO IT NOW has an administrative body composed of two members, chaired by Mr. Manfredi Andrea, owner of the company through an S.r.l. company of which he is the sole shareholder. The Company has appointed a Board of Statutory Auditors and has also engaged a specialized firm to audit its financial statements. DO IT NOW directly controls four companies, which represent the operational core of the Group.
In comparison with the sector peer group, DO IT NOW shows a high size positioning and a good solvency profile, supported by a balanced capital structure and a sustainable level of indebtedness. By contrast, profitability is weak, affected by the negative performance recorded in 2025, characterized by negative ROI and ROE. Over the period analyzed, the sector peer group shows a progressively improving solvency profile, with a reduction in indebtedness and a limited reliance on financial debt relative to equity. A balanced short-term financial structure is also confirmed, thanks to a consistent adequacy of current assets relative to liabilities. In terms of profitability, the sample shows positive performance, with return on invested capital growing until 2024 and stable thereafter, while return on equity remains broadly constant, confirming an adequate ability to generate earnings.
The macroeconomic projections released by the ECB in March for the euro area indicate that headline inflation will rise to 2.6% in 2026, mainly due to higher energy prices linked to the conflict in the Middle East, before settling at 2.0% in 2027 and 2.1% in 2028. Disruptions in commodity markets are weighing on real incomes and confidence, negatively affecting consumption and investment. In particular, annual real GDP growth is expected at 0.9%, 0.3 percentage points lower than the previous December projections, while for 2027 and 2028 it is estimated at 1.3% and 1.4%, respectively. In the medium term, the main driver of growth will continue to be domestic demand, supported by a stable labor market, by planned public spending on defense and infrastructure, and by the ongoing digitalization and the AI-driven investment cycle. On the external front, structural competitiveness challenges will lead to a continued loss of market share for the euro area. The current energy crisis highlights the need for an ecological transition that reduces dependence on fossil fuels. Moreover, to enhance competitiveness and financial integration in Europe, it will be essential to regulate and adopt the digital euro.
Sensitivity Analysis
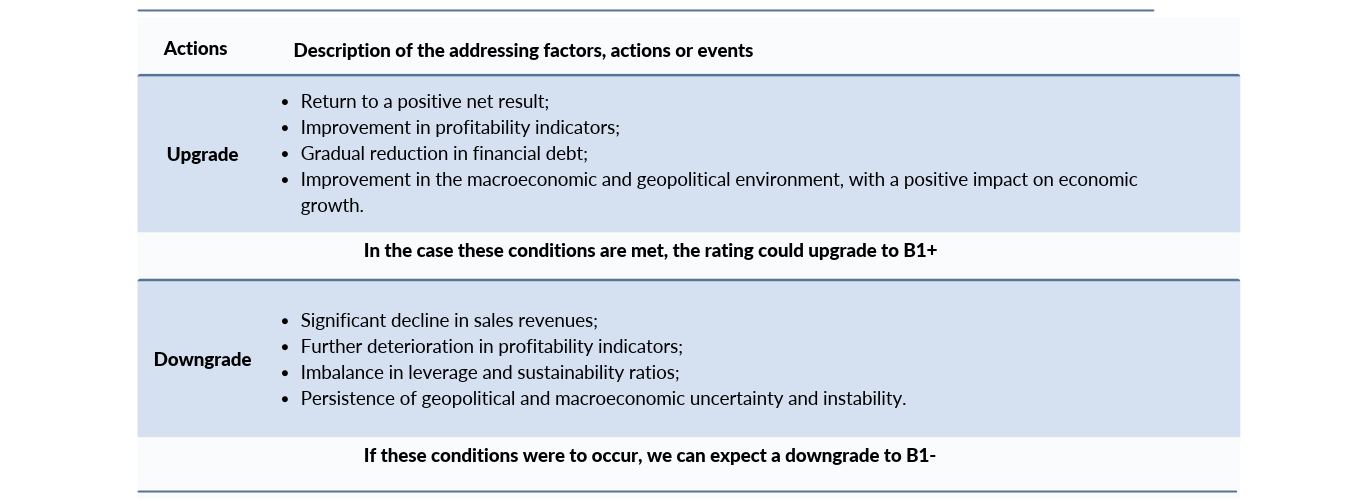
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated company purchased ancillary services from modefinance (Private Rating Solicited to a related third party of the rated entity). Modefinance guarantees that this purchase of ancillary activities does not constitute any conflict of interest.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Andrea Pausa, Rating Process Analyst
a.pausa@teamsystem.com