Solicited Corporate Credit Rating for È-DIENERGIA S.R.L.: B1 (Affirm)
Modefinance published the Solicited Corporate Credit Rating of È-DIENERGIA S.R.L. on the website and the rating assigned to the entity is B1 (Affirm). The analysis highlights that the Company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
È-DIENERGIA S.R.L. (hereinafter also “the Company”), is specialized in the supply of electricity and gas, operating nationwide while maintaining strong ties to Veneto and neighbouring regions. Founded in 2018, the Company initially focused on business customers but later expanded its services to residential customers, condos, and public administration customers.
Key Rating Assumptions
In 2025, È-DIENERGIA S.R.L. further strengthened its economic and financial profile, benefiting from the significant expansion of its customer base and the increase in energy volumes sold. Total supply points (PODs and PDRs) increased by 41.4%, while electricity and gas volumes grew by 37.9% and 52.7%, respectively. These dynamics supported revenues of EUR 82.4 million (+37.4% YoY) and a gross margin on electricity and gas of EUR 12.2 million (+19.6% YoY). From a balance-sheet and financial perspective, the Company reported a significant strengthening of shareholders’ equity, which increased from EUR 4.7 million to EUR 7.4 million, resulting in improved solvency indicators. The net financial position (NFP) also improved substantially, moving from net debt of EUR 0.4 million to a net cash position of EUR 7.3 million. In a competitive environment characterized by narrowing commercial spreads, volume growth enabled the Company to preserve profitability in absolute terms, with EBITDA remaining broadly stable at EUR 5.6 million and net profit amounting to EUR 3.6 million, despite a decline in margin percentages relative to revenues. The Company also demonstrated solid cash generation capabilities, with operating cash flow reaching EUR 8.0 million and cash and cash equivalents increasing from EUR 2.2 million to EUR 9.6 million. The limited level of capital expenditure allowed the Company to continue reducing financial debt and distributing dividends while maintaining a strong liquidity position. Available data for 2026 confirm the continued growth in traded volumes, with commercial margins showing solid resilience.
È-DIENERGIA S.R.L. is indirectly controlled by Ms. Liana Fantinato through the wholly-owned holding company FINVAR S.R.L., which exercises management and coordination activities over the Company. In June 2026, the governance structure was strengthened through the transition from a Sole Director to a two-member Board of Directors chaired by Ms. Liana Fantinato, who is also the Company’s ultimate beneficial owner. Statutory audit activities are entrusted to PricewaterhouseCoopers S.P.A., whose appointment was renewed for the 2026-2028 period.
In 2025, the Company maintained a favorable competitive position relative to its peer group, supported by strong revenue growth and profitability levels above sector medians. Solvency indicators continued to improve, although they remain slightly below those of comparable companies. Within a sector characterized by generally balanced capital structures and adequate liquidity profiles, the Company continues to stand out for its growth capacity and profitability performance.
In the first half of 2026, the Italian economy continued to expand at a moderate pace, supported primarily by the services sector, while manufacturing remained affected by weak external demand and persistently high energy costs. According to the Bank of Italy projections, GDP is expected to grow by 0.5% in both 2026 and 2027, accelerating to 0.8% in 2028. Nevertheless, uncertainty persists, driven by geopolitical tensions, the evolution of energy commodity prices and trends in international trade.
With regard to the energy sector, global electricity demand continues to increase, supported by the expansion of renewable energy sources and the progressive electrification of consumption. The competitive environment, however, remains influenced by energy market volatility and geopolitical tensions affecting key supply routes and producing regions. In Italy, the continued reliance on natural gas for electricity generation represents a source of exposure to energy price fluctuations, which keeps a high level of attention on the margins of sector operators, both on profitability and cost management.
Sensitivity Analysis
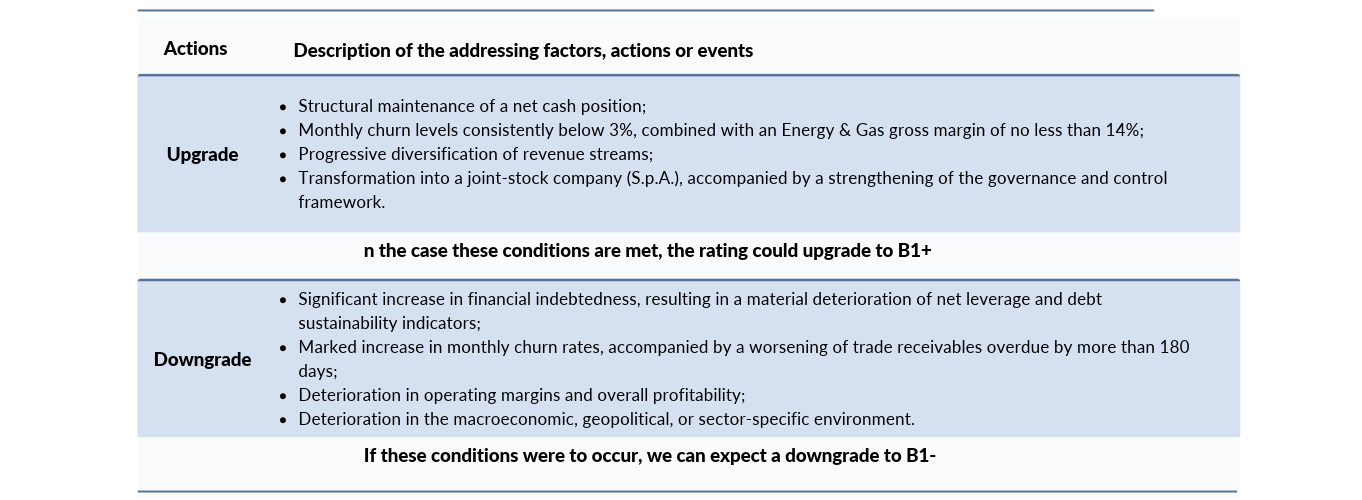
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
Some amendments were applied to the credit rating report and related press releases after the notification process was completed.
The rated entity is not a buyer of ancillary services provided by modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Andrea Pausa, Rating Process Analyst
a.pausa@teamsystem.com