Solicited Corporate Credit Rating for E.SMART S.R.L.: B1- (Affirm)
modefinance published the Solicited Corporate Credit Rating of E.SMART S.R.L. on the website and the rating assigned to the entity is B1- (Affirm). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
E.SMART SRL (hereinafter also referred to as "the Company") is an Italian company active in the sale of electricity and natural gas since 2005, with a strong focus on innovation, sustainability, and service quality. The Company positions itself as a trusted energy partner for residential and business customers, offering tailored solutions and competitive tariffs. Although operating nationwide, its activities are heavily concentrated in Northern Italy, particularly in Milan. In February 2026, E.SMART acquired 100% of Evolia S.R.L. as part of a broader corporate reorganization. The transaction expands the Group’s operating scope, strengthening its presence in energy services and the residential segment.
Key Rating Assumptions
In 2025, E.SMART reported an overall solid financial profile, with significant revenue growth and a marked improvement in margins and net profit. Despite the increase in leverage resulting from higher liabilities, the Company benefits from limited financial debt, a net cash position of €6.48 million and an improving liquidity profile. Profitability indicators remain at overall adequate levels.
The Company has a clearly defined ownership structure, with FEN ENERGIA S.P.A. as the majority shareholder, holding 75% of the share capital. The remaining 25% is held by Mr. Guido Ghirardi, who also serves as Chairman of the Board of Directors. During 2026, E.SMART completed the acquisition of 100% of the share capital of Evolia S.R.L., thereby gaining full control of the acquired entity.
Compared with its peer group, the Company has a favourable position in terms of scale, as measured by revenue, while its solvency metrics are broadly in line with sector medians. Profitability, however, is below the median of comparable companies. Overall, the peer group shows a progressive strengthening of its solvency profile, accompanied by slightly improving liquidity indicators that remain at adequate levels. Return on equity also shows a positive trend, remaining at adequate levels overall.
During 2026, the Italian economy continues to experience subdued growth amid heightened geopolitical uncertainty and rising energy prices. Following moderate growth in the first quarter, economic activity has shown signs of slowing, affected by weaker consumption and investment as well as persistent international tensions. According to the latest projections by the Bank of Italy, GDP is expected to grow by 0.5% in 2026, 0.4% in 2027 and 0.9% in 2028, while inflation is projected to rise in the short term, mainly due to higher energy prices. Meanwhile, the global energy market continues to undergo a structural transformation, driven by the increasing electrification of consumption and the rapid expansion of renewable energy sources.
Following an increase of approximately 3% in global electricity demand in 2025, the International Energy Agency (IEA) forecasts growth of 3.6% in 2026 and 3.8% in 2027, driven primarily by industry, data centres, electric mobility and air conditioning. Having represented approximately one-third of global electricity generation in 2025, renewables are expected to overtake coal-fired generation during 2026. In Italy, electricity demand stood at approximately 311 TWh in 2025, broadly unchanged from the previous year, with renewable energy sources covering 41% of consumption. Overall, the energy sector continues to benefit from the structural prospects associated with electrification and the transition towards low-emission energy sources, while remaining exposed to commodity price volatility, geopolitical tensions and energy supply security risks.
Sensitivity Analysis
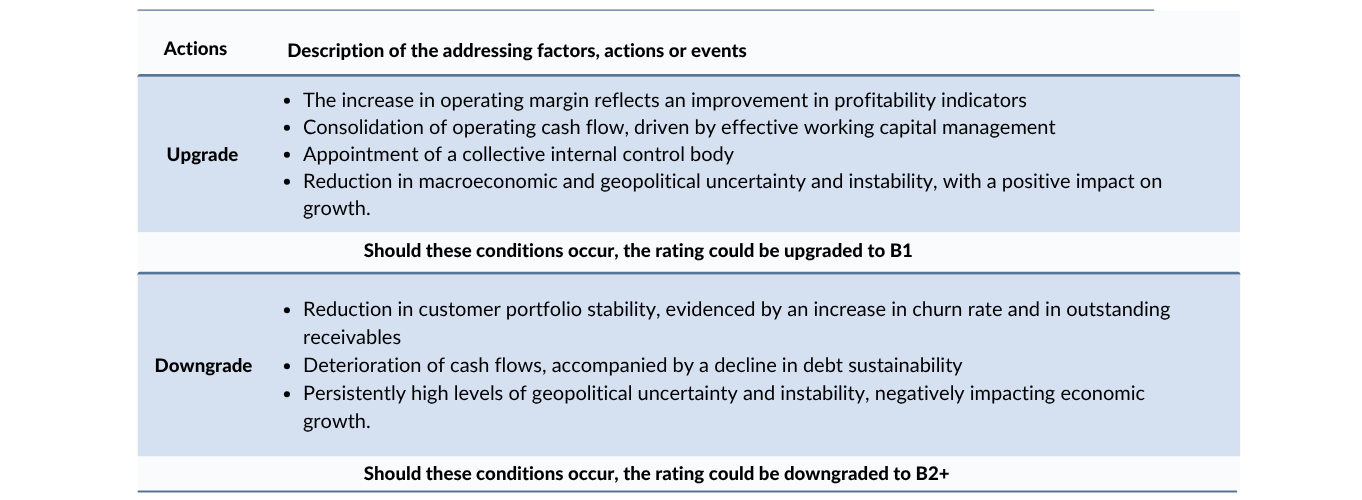
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated company purchased ancillary services from modefinance (preliminary rating). Modefinance guarantees that this purchase of ancillary activities does not constitute any conflict of interest.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the people reported above, modefinance Ratings will provide the appropriate information and if necessary, the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity and should be relied upon to a limited degree. The issued rating is subject to ongoing monitoring until withdrawal.
Contacts
Head Analyst - Mattia Dunnhofer, Rating Analyst
mattia.dunnhofer@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com