Solicited Corporate Credit Rating for ENERFIN S.P.A.: B1 (First Issuance)
modefinance published the Solicited Corporate Credit Rating of ENERFIN S.P.A. on the website and the rating assigned to the entity is B1 (First Issuance). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
ENERFIN S.P.A. (hereinafter also referred to as "the Company"), established in 2013, operates in the energy market, focusing primarily on the provision of energy services to companies, SMEs, and self-employed professionals. Headquartered in Rome, the Company supports its customers in developing projects aimed at improving energy efficiency, reducing consumption and achieving sustainability and decarbonization targets. Its activities are based on an analysis of customers’ energy consumption profiles to identify the main areas for efficiency improvement, thereby enabling the implementation of targeted measures to optimize consumption. Its offering includes, among other services, technological solutions for energy efficiency, such as photovoltaic systems and innovative air-conditioning and heating systems, designed to reduce environmental impact and improve customers’ operational efficiency. No adverse findings have been identified in relation to the Company or its shareholders.
Key Rating Assumptions
In 2025, Enerfin reported an overall balanced financial profile, supported by the strengthening of shareholders’ equity, which increased from €3.83 million to €5.14 million. Bank debt rose to €3.26 million due to new financing facilities intended, among other purposes, to fund the investment plan, bringing net financial debt to €2.2 million. Nevertheless, the net financial debt-to-EBITDA ratio of 1.16x confirms the Company’s sound debt-servicing capacity. The liquidity profile remained adequate, with both the current ratio and quick ratio standing at 1.08x. From an income statement perspective, revenues increased by 29% to €117.42 million, while EBITDA reached €1.9 million, up 42.43%. The Company closed the year with a net profit of €1.31 million, compared with €840 thousand in 2024, while ROI and ROE improved to 10.50% and 25.40%, respectively.
ENERFIN S.P.A. has a straightforward ownership structure, with Mr. Francesco Borrelli and Mr. Massimiliano Borrelli holding a 50% interest in the Company, as members of its management team and shareholders. The Company also has a collegial supervisory body, namely a Board of Statutory Auditors chaired by Mr. Salvatore Di Carlo.
Compared with the other companies in its peer group, Enerfin demonstrates a solid size positioning. In terms of solvency, however, the Company ranks slightly below the sector median, while maintaining indicators consistent with an overall sustainable financial profile. Profitability is above the sector median, at adequate levels.
Between late 2025 and 2026, the energy market has been characterised by growing electricity demand and the rapid expansion of renewable energy, particularly solar photovoltaic and wind power. However, fossil fuels continue to play a central role, while geopolitical tensions in Iran and restrictions affecting the Strait of Hormuz are increasing energy-price volatility and inflationary pressures. In Italy, renewable sources account for 41% of electricity consumption. Nevertheless, the country’s continued reliance on natural gas is keeping prices high and has prompted the Government to postpone the closure of certain coal-fired power plants in order to safeguard energy security.
From a macroeconomic perspective, the Italian economy recorded weak growth in the first quarter of 2026, driven primarily by the services sector. Manufacturing, household consumption, and investment were adversely affected by rising energy costs and international uncertainty. The Bank of Italy forecasts GDP growth of 0.5% in both 2026 and 2027, followed by 0.8% in 2028.
Sensitivity Analysis
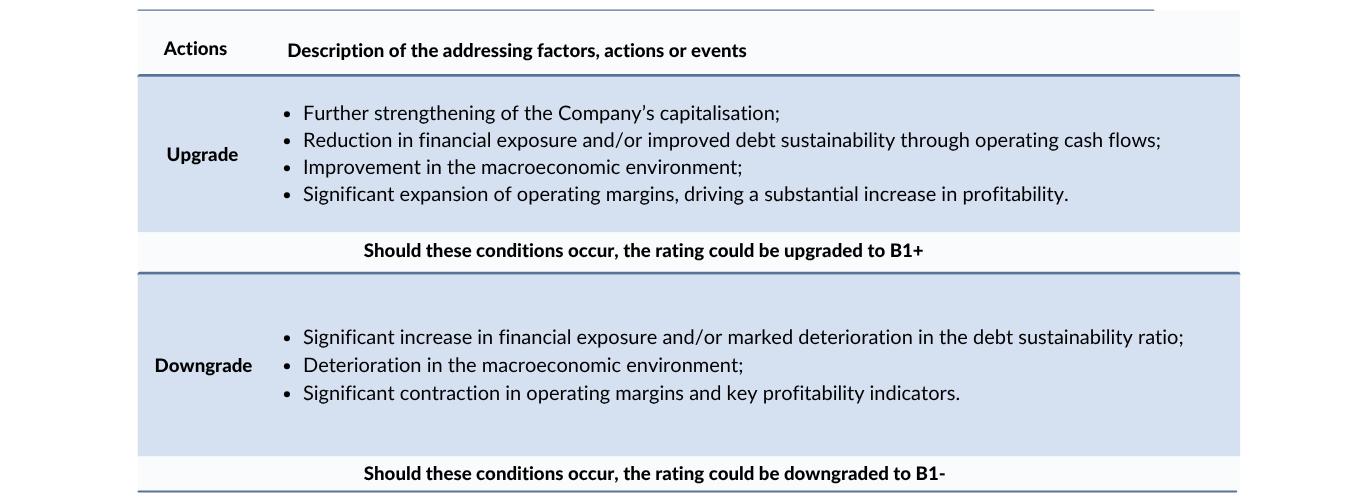
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process.
The rated company purchased ancillary services from modefinance (preliminary rating). Modefinance guarantees that this purchase of ancillary activities does not constitute any conflict of interest.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the people reported above, modefinance Ratings will provide the appropriate information and if necessary, the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity and should be relied upon to a limited degree. The issued rating is subject to ongoing monitoring until withdrawal.
Contacts
Head Analyst - Mattia Dunnhofer, Rating Analyst
mattia.dunnhofer@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com