Solicited Corporate Credit Rating for ESA ITALIA S.R.L.: B1 (Affirm)
modefinance published the Solicited Corporate Credit Rating of ESA ITALIA S.R.L. on the website and the rating assigned to the entity is B1 (Affirm). The analysis highlights that the company has an adequate economic and financial situation, demonstrating an average capability to meet its financial obligations and remaining minimally affected by adverse economic scenarios.
ESA ITALIA SRL (hereafter “ESA ITALIA” or “the ESA Group”) is a holding company based in Chieti, at the head of the ESA Group, primarily active in the sale of electricity and gas through ESA SPA SB; this offering is complemented by installation, transformation and expansion services for thermal, hydro-sanitary, electrical, photovoltaic and cogeneration systems carried out by ESA SERVICE 24H SRL in its capacity as an ESCO, as well as by boiler and air-conditioning maintenance services provided by ESA SERVICE SRL. The Group's main subsidiary, ESA SPA, established in 2005, operates as a Dispatching User and offers integrated, qualified energy assistance services through a network of 80 Energy Points concentrated mainly in Central Italy and Sicily. As of December 2025, ESA SPA's customer portfolio reached 84 thousand units, recording a 12% CAGR over 2023-2025, driven primarily by portfolio acquisitions and, to a lesser extent, internal commercial development. The 2025 churn rate trend improved for electricity (40%) while worsening for gas (41%), with both figures above sector benchmarks published by ARERA.
Key Rating Assumptions
ESA ITALIA SRL's turnover grew from 131.1 million euros to 167.6 million euros in 2025 (+28% YoY), driven by increased volumes of electricity (582.9 GWh, +27%) and natural gas (31.3 million Smc, +30%) marketed by ESA SPA SB, supported by the acquisition of over 20,000 retail supply points in Central Italy between 2024 and 2025. The energy efficiency segment (ESA SERVICE and ESCO ESA SERVICE H24) generated 8.4 million euros in revenues (+0.8% YoY). EBITDA declined from 11.4 million euros to 9.0 million euros (-22% YoY), reflecting workforce strengthening and a decline in the ESCO's margin profile, with EBITDA margin falling from 39% to 11% as maintenance services gained weight relative to photovoltaic projects. Net profit nearly halved, from 7.8 million euros to 5.9 million euros, further impacted by amortization of customer portfolios and lower proceeds from the disposal of ecobonus tax credits. Profitability indicators remain adequate, albeit declining (ROI 9.23%, ROE 17.06%). The Net Financial Debt/EBITDA ratio rose from 0.41x to 1.48x, reflecting the deterioration of the Group's Net Financial Position (from 4.2 million euros to 13.2 million euros), although it remains at balanced levels. To safeguard against potential financial needs, the Group holds readily realisable financial instruments amounting to 4.2 million euros (5.4 million euros in 2024) and interest-bearing financial receivables from related parties of 4.4 million euros. The strengthening of shareholders' equity to 23.5 million euros (+4.0 million euros YoY) improved both financial leverage (from 1.2x to 1.0x) and overall leverage (from 3.18x to 2.33x), the latter also benefiting from the significant reduction in trade exposures. The Group's cash and cash equivalents decreased from 19.1 million euros to 10.2 million euros in 2025 (-8.9 million euros), due to the combined effect of negative net operating cash flow of 5.2 million euros and total investments of 5.5 million euros. The negative operating cash flow is mainly attributable to the structuring of financing arrangements to replace intra-group trade payment extensions and, to a lesser extent, to longer collection times related to energy efficiency services. Investments include the acquisition of customer portfolios, increased security deposits, and financing granted to the associated company ESA POWER Holding. On the financial front, gross debt remained unchanged at 23.5 million euros (+0.2 million euros YoY): bank loans were repaid early and replaced with medium-long term mortgage loans, extending the debt duration. The ageing analysis of ESA SPA SB shows a deterioration in the qualitative mix of overdue receivables which, in a context of significant customer portfolio expansion, will require close monitoring of credit risk to preserve credit quality and mitigate potential negative effects on prospective cash flows. ESA SpA SB’s management of credit lines appears sound, with no disputes, serious irregularities, or episodes of financial strain observed throughout the period under analysis.
ESA ITALIA's share capital, amounting to €2 million, is held by three companies traceable to the Serpellini family and, in particular, to Mr. Walter Serpellini, who serves as Sole Director of both ESA ITALIA and its subsidiary ESA SpA SB. The Sole Director is supported by a Sole Statutory Auditor, Mr. Marino Mauro, and by a leading auditing firm responsible for auditing the annual and consolidated financial statements (the latter prepared starting from the 2024 fiscal year). As part of the Group's reorganization aimed at separating commercial activities from renewable energy production, in September 2025 ESA ITALIA transferred its stake in ENERGY SOLAR Srl (acquired in April 2024) to ESA POWER HOLDING S.r.l. (hereafter ESA POWER), which became the new entity for the Group's renewable energy activities. ESA POWER is likewise controlled by the Serpellini family, with a 26% stake held by ESA ITALIA and the remainder held by the corporate vehicles controlling ESA ITALIA. No adverse findings were identified regarding the shareholders, the Sole Director, or ESA ITALIA.
ESA ITALIA shows a strong size positioning relative to its peer group, reinforced by the expansion of ESA SPA SB's customer portfolio. Solvency has improved relative to the sector median, reaching an adequate level thanks to the significant reduction in Days Payable Outstanding (DPO) compared to 2024. Lastly, profitability contracted during the period, standing below the sector median but remaining fully adequate. The peer group's solvency indicators remain adequate and improving, benefiting from capital strengthening and greater stabilization of energy prices following the "energy crunch." Sector liquidity management is balanced, with current and quick ratios increasing throughout the entire period under analysis. After three consecutive years of growth over the 2022-2024 period, sector profitability contracted slightly in 2025 while remaining more than adequate.
Between late 2025 and 2026, the global energy market continues to evolve in a context of strong growth in electricity demand and rapid expansion of renewable energy sources, particularly solar and wind power. Despite the energy transition, oil and gas continue to play a central role in the global energy mix. Geopolitical tensions related to Iran and restrictions in the Strait of Hormuz have increased market volatility, pushing Brent prices above USD 110 per barrel and generating global inflationary pressures.
In Italy, electricity consumption in 2025 reached approximately 311 TWh, with a renewable share of 41% and installed capacity of around 83.5 GW. However, strong dependence on gas continues to keep energy prices high, prompting the Government to postpone the closure of some coal-fired plants to ensure energy security. Overall, the combination of rising demand, the expansion of renewables, and geopolitical volatility, particularly concerning Iran, defines a highly dynamic global and Italian market context that is subject to significant price risks.
In the first quarter of 2026, the Italian economy continued to grow at a moderate pace, in an international context marked by a sharp increase in geopolitical uncertainty. Activity was mainly supported by services, partly due to the temporary boost from the Winter Olympic Games, while manufacturing showed signs of slowing linked to rising energy costs and weak foreign demand. Household consumption grew moderately, affected by worsening confidence and the erosion of purchasing power linked to rising energy prices; investment slowed, with a limited positive contribution due to uncertainties in the macroeconomic outlook and the fading of incentives in the residential sector. According to the Bank of Italy's most recent projections, Italian GDP is expected to grow by 0.5% in 2026 and 2027, before accelerating to 0.8% in 2028. Economic activity is expected to be supported in the medium term by the gradual easing of inflationary pressures and the recovery of domestic demand, while in the short term it remains exposed to downside risks related to the evolution of the conflict in the Middle East, energy commodity prices, and international trade.
Sensitivity Analysis
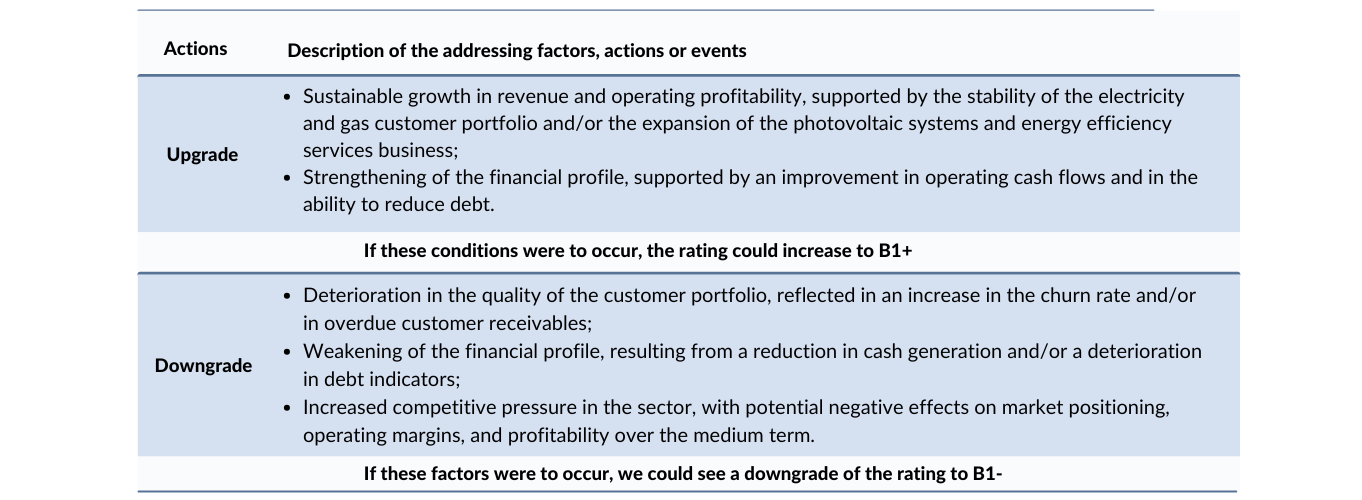
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated entity is not a buyer of ancillary services provided by modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Carmela Santomarco, Rating Analyst
carmela.santomarco@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com