Solicited Corporate Credit Rating for ETC INVEST S.P.A.: A3- (Affirm)
modefinance published the Solicited Corporate Credit Rating of ETC INVEST S.P.A. on the website and the rating assigned to the entity is A3- (Affirm). The analysis revealed that the company's capacity to meet its commitment on financial obligations is strong.
ETC INVEST S.P.A. (hereinafter also referred to as "the Company" or "the Group"), the holding of the multinational Italian group “Export Trading Cooperation” (ETC), is a joint-stock company providing consulting services in project finance and trade finance, with an exclusive focus on African markets, both directly and through the Group's subsidiaries. The Company specializes in trade finance and supply chain activities, supporting trade with Sub-Saharan African countries and investment projects. Since its foundation, the Company has pursued international expansion through the creation of representative offices, subsidiaries, and funds across Europe and Africa, including the Regional Bureau Africa based in Cotonou (Benin). Moreover, as an active member of SWIFT (Society for Worldwide Interbank Financial Telecommunication), the Group facilitates interbank financial messaging between European and African financial institutions. Thanks to its presence in Africa and its combined expertise in trade finance and supply chain management, the ETC Group has become a leading point of reference for banks and industrial/commercial groups in managing supply chains and investment projects across sectors ranging from agribusiness and industry to transport and green energy.
Key Rating Assumptions
The economic and financial situation of the Company is adequate, with a strong condition of solvency (leverage = 0.03x and financial leverage = 0.01x) and a good level of liquidity. The Net Financial Position (€365 thousend) to EBITDA (€570 thousend) ratio recorded a significant improvement, declining from 4.05x to 0.64x, driven by an increase in cash and cash equivalents, which was in turn supported by strong operating cash flow generation (3.6 million euros). Turnover registered an expansion (3.2 million euros; +5%), but profitability remains on an improving trajectory.
In April 2024, the Shareholders' Meeting resolved to transition from the previous two-tier system to a one-tier corporate governance model, aiming to align the company’s governance with the best international practices. The Company is audited by an external auditor. ETC INVEST S.P.A. is controlled by Monte Paschi Fiduciaria S.p.A., which is ultimately owned by the Italian Republic. The company also holds controlling interests in a Cameroonian company that serves as a regional hub for Central-Western Africa.
Compared with the reference peer group, the Company presents a strong positioning in terms of size and solvency. On the other hand, profitability is lower than the sector’s median, but the ETC Group’s business is unique and the applicable NACE code does not fully reflect the activity actually performed. The reference peer group continues to exhibit balanced indicators of solvency, liquidity and profitability.
The Italian management consulting sector continued to grow in 2025, driven by increasing demand for digital transformation, artificial intelligence, sustainability, cybersecurity, and regulatory advisory services. The PNRR (National Recovery and Resilience Plan) remains an important driver of consulting demand, while the market is expected to grow by approximately 5.7% annually through 2026, outperforming overall Italian GDP growth.
At the international level, Africa offers attractive opportunities for consulting services, supported by increasing foreign investment, particularly in infrastructure, renewable energy, and services, as well as the implementation of the AfCFTA (African Continental Free Trade Area). In 2026, the continent is expected to remain one of the world's fastest-growing regions, supported by strong growth in services, infrastructure, and natural resources. However, some risks remain, including still-elevated inflation in certain countries, geopolitical tensions, and particularly political instability in the Sahel and parts of West Africa. Overall, the medium-term outlook remains positive, driven by growing demand for digitalisation, sustainability, business transformation, and support for international investments.
Sensitivity Analysis
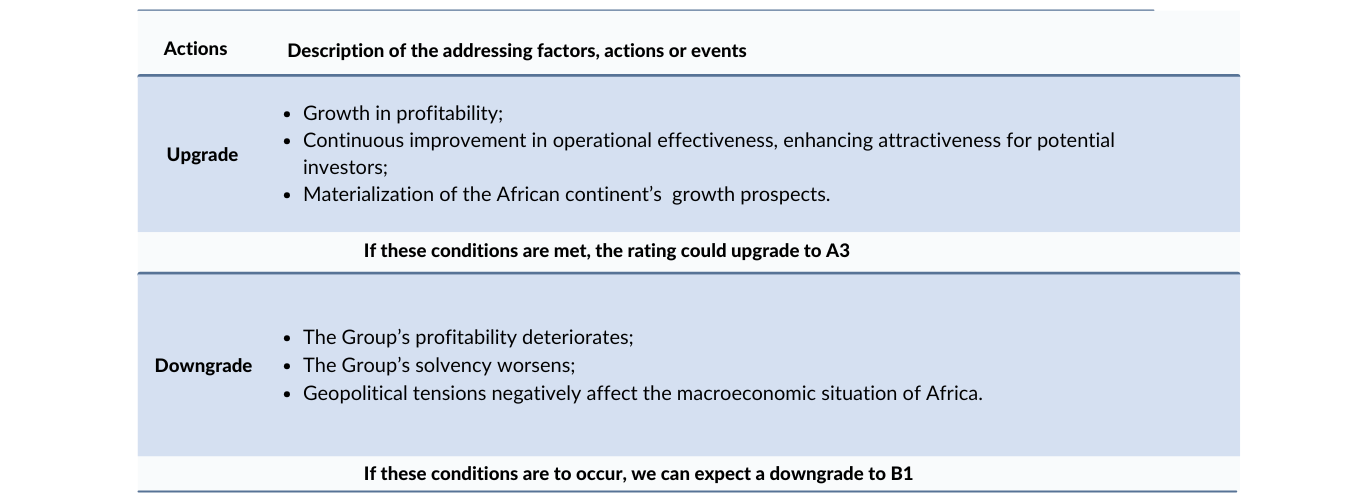
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
Deadline for the appeal process expired without the notification of factual errors by the Rated Entity.
The rated entity is a buyer of ancillary services provided by modefinance (credit risk software and sustainability assessment). modefinance ensures that such situation does not imply a conflict of interest in the issuance of the present credit rating.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary, the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com