Solicited Corporate Credit Rating for GP HOLDING S.R.L.: B1 (Affirm)
modefinance published the Solicited Corporate Credit Rating of GP HOLDING S.R.L. on the website and the rating assigned to the entity is B1 (Affirm). The analysis revealed that the company has an adequate economic-financial situation with average capability of repaying financial obligations and it is little affected by adverse economic scenarios.
GP HOLDING S.R.L. (hereinafter “GPH”), operating in Monza since 2018, is a financial holding company specialized in investing in and managing equity interests in companies primarily operating in the energy sector. As of today, GPH holds four equity interests, the most significant of which is its 100%-owned subsidiary Earth Energy S.r.l., engaged in the import and wholesale trading of natural gas and electricity on the Italian market. The latter recorded a significant increase in revenues in 2025, further strengthening its position within the Italian energy market.
Key Rating Assumptions
GP HOLDING S.R.L. continues to exhibit a sound financial and economic profile, with no significant areas of concern. Leverage remains close to zero, reflecting the Company's limited level of liabilities. No financial debt is outstanding, resulting in a net cash position, consistent with previous years. From a profitability perspective, the Company reported a net loss for the year, unlike FY2024 and FY2023, when financial income contributed positively to earnings. It should be noted that GPH's financial and economic performance is closely linked to that of its subsidiary Earth Energy (“EE”). In 2025, EE increased its business volume, delivered solid profitability levels, and maintained a balanced capital and financial structure, achieving a B1+ rating assessment. The Company's main operating subsidiary ranks among the largest players within its sector peer group, demonstrating a strong ability to generate significant revenues while further strengthening its growth trajectory over recent years. Profitability indicators also remain above the peer-group average. In terms of solvency, positioning is somewhat weaker than the sector median, reflecting a still relatively elevated leverage ratio. Nevertheless, the overall use of financial debt remains balanced and consistent with the Company's capital structure.
GPH operates as an investment holding company and controls Earth Energy (“EE”), as well as GP Venture since 2026, while also holding minority stakes in two additional companies. The sole shareholder of GPH also serves as its sole director and acts as Chief Executive Officer of the aforementioned subsidiary. No supervisory or statutory control bodies are in place.
The sector peer group has shown a gradual improvement in financial and capital structure metrics over the period under review, supported by a progressive reduction in leverage. Overall capitalization remains balanced, while liquidity indicators have consistently maintained satisfactory levels. Profitability performance has remained stable and satisfactory throughout the period analyzed. Return on Equity (ROE) demonstrates a sustained ability to remunerate shareholders' capital, while Return on Capital Employed (ROCE) shows a gradual strengthening of operating profitability, confirming an overall sound level of profitability across the peer group. At the end of 2025 and throughout 2026, the global energy market remained in a phase of significant transformation, characterized by sustained growth in electricity demand and continued expansion of renewable energy capacity, particularly in solar and wind generation. At the same time, fossil fuels continue to play a crucial role in the global energy mix. Geopolitical tensions in the Middle East, particularly those involving Iran, have contributed to increased market volatility, affecting energy supply routes and pushing oil prices higher, with consequent increases in risk premiums across energy markets. These developments have generated inflationary pressures globally and influenced monetary policy decisions. In Italy, electricity consumption remained substantial, with renewable sources accounting for an increasing share of generation; however, the country's significant dependence on natural gas continues to exert upward pressure on energy prices. Overall, the combination of growing demand, the ongoing energy transition, and geopolitical uncertainty has created a highly dynamic market environment characterized by elevated price and supply risks.
During the first months of 2026, the Italian economy continued to expand at a moderate pace amid a global environment marked by heightened geopolitical uncertainty. Economic activity was primarily supported by the services sector, also benefiting from the temporary boost associated with the Winter Olympic Games, while manufacturing showed signs of weakness due to rising energy costs and subdued external demand. Household consumption increased moderately, affected by weaker consumer confidence and reduced purchasing power resulting from higher energy prices. Investment activity also slowed, with positive contributions constrained by macroeconomic uncertainty and the gradual reduction of incentives within the residential sector. According to the latest projections from the Bank of Italy, Italian GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. Over the medium term, economic activity is expected to benefit from easing inflationary pressures and a recovery in domestic demand, although downside risks remain linked to developments in the Middle East conflict, energy commodity prices, and international trade dynamics.
Sensitivity Analysis
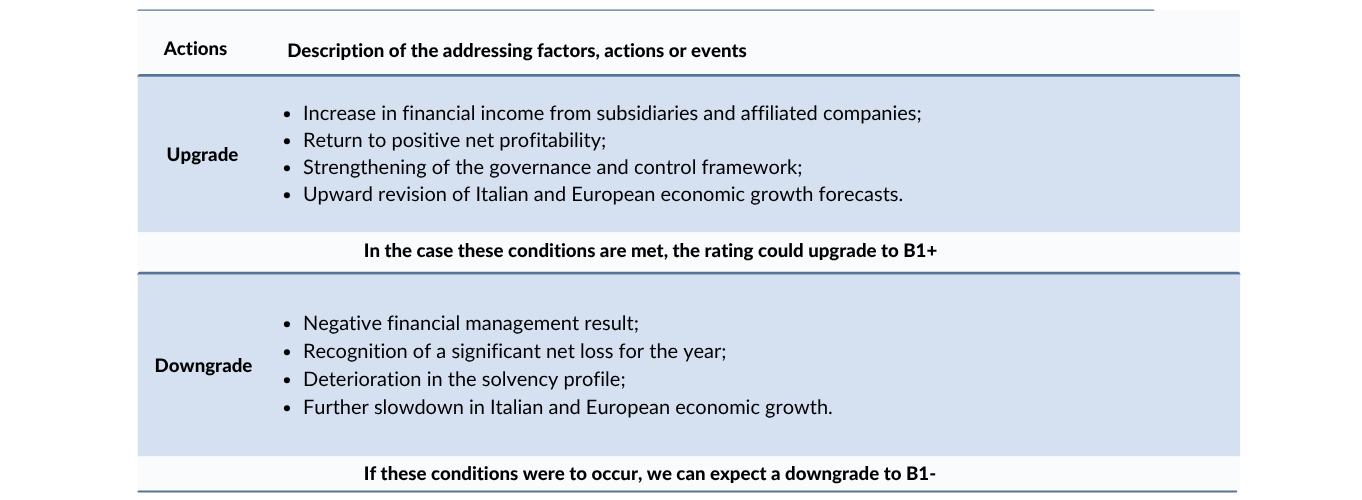
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. Modefinance did not provide any ancillary services to the entity.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com