Solicited Corporate Credit Rating for HAIKI+ S.P.A.: B1- (Affirm)
modefinance published the Solicited Corporate Credit Rating of HAIKI+ S.P.A. on the website and the rating assigned to the entity is B1- (Affirm). The analysis highlights that the company has an adequate capability to meet its financial obligations, whilst remaining moderately exposed to adverse economic conditions.
Haiki+ S.P.A. (hereinafter also referred to as "the Company" or "the Group") operates nationwide in the integrated environmental services sector, focusing on the management of non-hazardous special waste and the development of solutions for the circular economy and the ecological transition. Established following the demerger of Innovatec S.P.A. and listed on Euronext Growth Milan since 2025, the Group employs approximately 620 people and operates a network of 20 industrial plants, mainly located in Northern Italy, covering the entire waste management cycle. The Group is organised into five operating divisions: Haiki Mines (landfills for special and municipal waste), Haiki Cobat (logistics and treatment services for industrial consortia), Haiki Recycling (conversion of waste into new raw materials), Haiki Electrics (WEEE and photovoltaic panel recycling), and Haiki Metals (lead and alloy production).
Key Rating Assumptions
HAIKI+ Group confirms an overall adequate economic and financial profile. In 2025, the Group reported sales revenue of over €267 million, up from €181 million in 2024, with a solid operating margin of 16% of revenue. Net income also returned to positive territory, at €378 thousand, following a net loss of €2 million in the previous financial year. In terms of solvency, the Group strengthened its equity base, which increased to €49 million from €22 million. Net financial debt, although higher than in 2024 (€72 million versus €43 million), remains sustainable and at an adequate level relative to equity (1.45x) and EBITDA (1.67x). Liquidity indicators, however, require further attention, as they remain below equilibrium levels (current ratio of 0.80x).
The Company has a collegial Board of Directors, supported by a Board of Statutory Auditors and an independent statutory audit firm. It has also established a Supervisory Body pursuant to Legislative Decree No. 231/2001. Following its listing on Euronext Growth Milan (EGM), the majority of Haiki+'s shares is now represented by free float, while a minority stake is held by SG Holding S.R.L., which is associated with the Colucci family. Haiki+ Group has a complex organisational structure, comprising numerous subsidiaries directly or indirectly controlled by the Parent Company.
HAIKI+ Group maintains a strong size positioning, ranking among the largest Italian companies in the sector by revenue. Its positioning in terms of solvency and profitability is below the 50th percentile of the distribution, reflecting relatively high leverage and weak profitability indicators. The sector peer group analysed exhibits an adequate financial profile in terms of solvency and liquidity, with indicators at balanced levels. Profitability is also adequate, as reflected in ROCE and ROE performance.
In 2026, the waste management sector continues to be shaped by the progressive adoption of circular economy principles, regulatory developments and the need to expand waste treatment infrastructure. Growth opportunities stem from the expansion of recovery and recycling activities, greater value-chain integration, and the optimisation of plant capacity. However, operators' profitability remains dependent on the balance between operating costs, waste treatment fees, available authorised capacity and the commercial value of recovered materials.
From a macroeconomic perspective, the ECB's March projections indicate euro area GDP growth of 0.9% in 2026, down from previous estimates, and inflation of 2.6%, driven by higher energy prices amid tensions in the Middle East. Growth is expected to recover gradually over the following two years, reaching 1.3% in 2027 and 1.4% in 2028, while inflation is projected to decline to 2.0% and 2.1%, respectively. The economic environment remains affected by pressures on real incomes, consumption and investment, while the outlook is supported by domestic demand, public spending and technology-related investment. Energy market tensions further underscore the need to accelerate the ecological transition and reduce dependence on fossil fuels.
Sensitivity Analysis
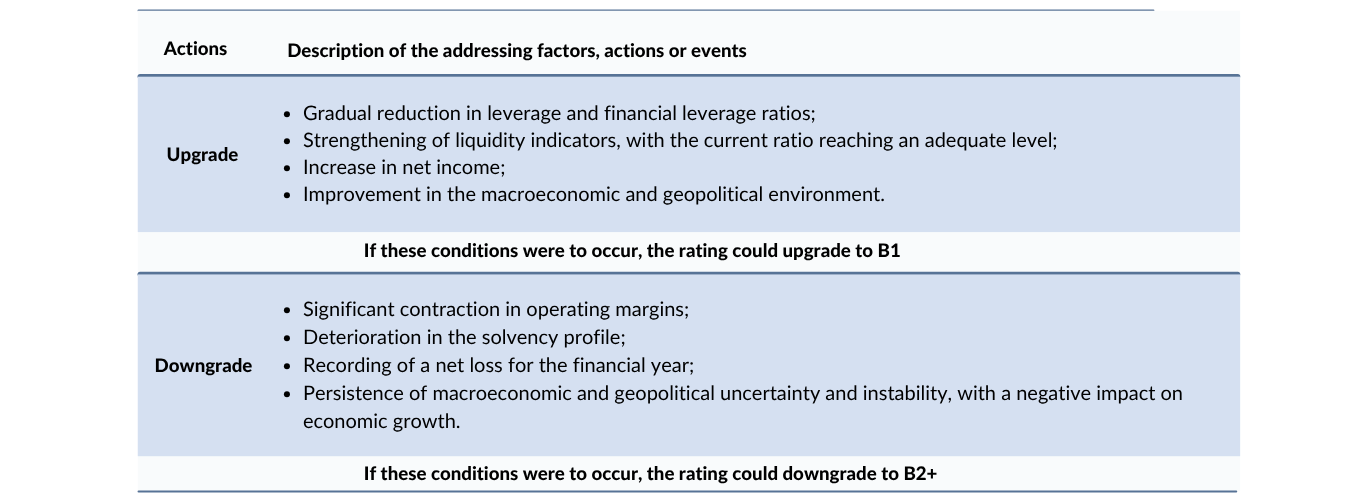
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process.
The rated entity is a buyer of ancillary services provided by modefinance (Private Rating Solicited to a related third party of the rated entity). This does not represent a conflict of interests.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com