Solicited Corporate Credit Rating for MARE ENGINEERING GROUP S.P.A.: A3- (Affirm)
modefinance published the Solicited Corporate Credit Rating of MARE ENGINEERING GROUP S.P.A. on the website and the rating assigned to the entity is A3- (Affirm). The analysis highlights that the Company has a solid capacity to fulfill its financial obligations.
MARE ENGINEERING GROUP S.P.A. (also referred to as “Mare Group” or “the Group”) is an Italian high-tech engineering hub operating in the Aerospace & Defence, Industry & Transportation and Infrastructure & Building sectors, with solutions based on artificial intelligence, extended reality, IoT and digital twin technologies. Listed on Euronext Growth Milan since 2024, the Group has started the process to move to Euronext Milan, STAR segment - subject to the fulfillment of the relevant requirements.
Key Rating Assumptions
FY2025, the first financial year prepared under IFRS, marks a significant step up in scale for Mare Group: driven by intense M&A activity, consolidated revenues rose to €59.1 million (+45.1%) and to €85.0 million on a pro forma basis, while IFRS EBITDA stood at €4.2 million, weighed down by €11.7 million of non-recurring items mainly related to extraordinary transactions; excluding these items, adjusted EBITDA reached €15.9 million (26.9% of revenues). The net result, a loss of €8.3 million, also reflects write-downs of €9.5 million. Financed mainly through new medium and long-term credit lines, growth brought reported net financial debt to €69.9 million, against shareholders’ equity of €45.9 million, which ensures an adequate balance with third-party funding, while the adjusted Net Financial Position (NFP) reported by the Group, equal to €24.2 million, implies a ratio to adjusted EBITDA of around 1.5x.
Cash and cash equivalents increased from €2.6 million to €52.9 million thanks to financing activities, supported by new medium and long-term loans, including the facility granted by Generali Asset Management SGR for the Eles transaction, and by capital increases of €7.1 million. This was set against €8.5 million absorbed by operating activities, due to the growth in receivables and inventories, and net investments of €27.7 million, mainly allocated to the tender offer for Eles, corporate acquisitions and the development of technology platforms.
The outlook for 2026 appears positive: the half-year results confirm the operating improvement, with adjusted EBITDA at 20.9% and EBIT back in positive territory, and in the period the Group secured orders of €103.6 million, of which €72.7 million to be executed within the year and €30.9 million relating to framework agreements and multi-year contracts that provide visibility for subsequent years, in addition to a commercial pipeline of around €124 million with a growing contribution from Aerospace & Defence. The €10 million capital increase subscribed by Invitalia and DVC2 strengthens the capital structure, and guidance points to revenues of €95–100 million and EBITDA of €21–22.5 million.
Mare Group’s governance and control framework is in line with best practice, with a collegial Board of Directors, Board of Statutory Auditors and Supervisory Body under Legislative Decree 231/2001, and the audit entrusted to Deloitte & Touche. The process towards Euronext Milan and, subject to the fulfilment of the relevant requirements, towards the Euronext STAR Milan segment, will lead to the adoption of even stricter governance and transparency standards. In 2026 the shareholder base was strengthened through the reserved capital increase: Invitalia, through the Fondo Cresci al Sud, increased its stake to 9.2% and DVC2 entered with 7.0%. The Group’s structure remains in constant evolution as a result of intense M&A activity.
Mare Group confirms a size positioning above the peer group median, thanks to the strong growth of its perimeter, while solvency and profitability are below sector levels. Solvency is weighed down by the increase in debt to support acquisitions and the recognition of lease liabilities required by IFRS. Profitability is affected by the loss for the year, largely attributable to extraordinary charges and write-downs, and by the only partial consolidation of the margins of acquired companies. The peer group, by contrast, shows satisfactory solvency, with leverage indicators steadily improving, and profitability levels rising in 2025.
In the first quarter of 2026 the Italian economy continued to grow at a moderate pace, amid strong geopolitical uncertainty. Services supported activity, while manufacturing slowed due to higher energy costs and weak foreign demand, and consumption and investment were held back by declining confidence and uncertainty about the macroeconomic outlook. The Bank of Italy forecasts GDP growth of 0.5% in 2026 and 2027 and 0.8% in 2028, exposed to downside risks linked to the conflict in the Middle East, energy prices and international trade.
Sensitivity Analysis
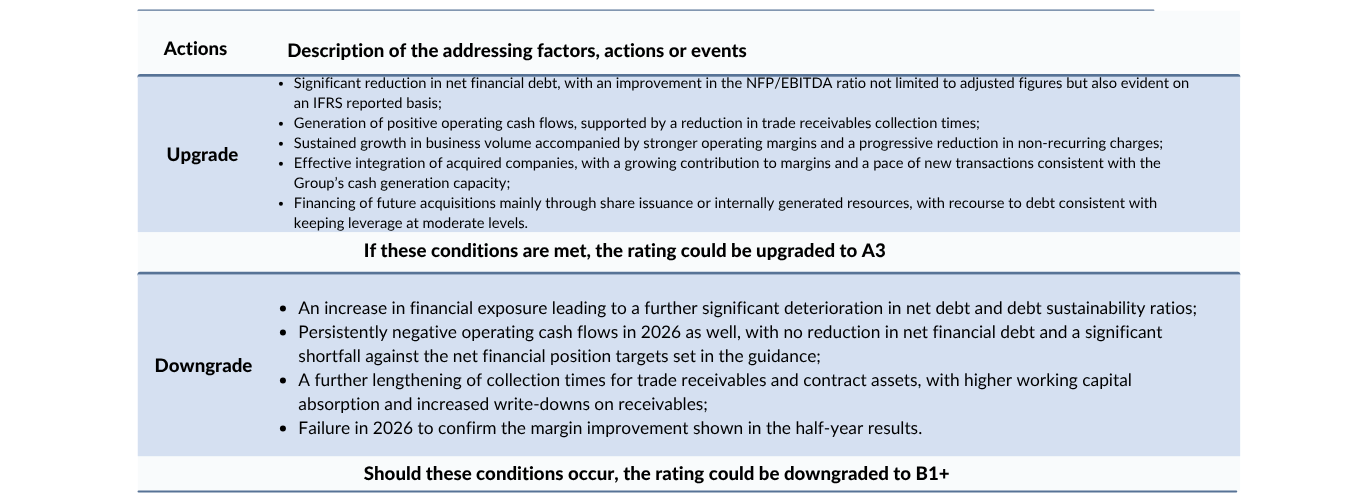
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated entity is not a buyer of ancillary services provided by modefinance
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary, the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com