Solicited Corporate Credit Rating for MIWA ENERGIA S.P.A. (Affirm)
modefinance published the Solicited Corporate Credit Rating of MIWA ENERGIA S.P.A. on the website and the rating assigned to the entity is B1- (Affirm). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
MIWA ENERGIA S.p.A. (hereinafter also referred to as the “Company”) is a national operator active in Italy’s liberalized energy market, specializing in the supply of natural gas and electricity to retail customers and small and medium-sized enterprises (SMEs). Over the years, the Company has developed a widespread commercial presence across the country, complementing its traditional energy services with additional solutions in the fields of energy efficiency and mobile telecommunications. In 2025, MIWA Energia further strengthened its growth trajectory, generating revenues in excess of €30 million and managing a portfolio of approximately 35,000 active customers, supported by the expansion of its sales network and the progressive development of a multi-service offering.
Key Rating Assumptions
MIWA ENERGIA S.p.A. further strengthened its capital structure in 2025, supported by retained earnings and a concurrent reduction in financial debt, resulting in an improvement in net financial position (NFP), also driven by higher cash and cash equivalents. Short-term financial equilibrium remains satisfactory, with trade receivables representing the main component of current assets. Particular attention should be paid to monitoring overdue receivables and the collection of certain incentive-related credits. From a profitability perspective, the Company continued to record growth in sales revenues, while operating margins improved significantly, supported by adequate profitability indicators.
MIWA ENERGIA S.p.A. has a relatively streamlined corporate structure, with control concentrated in Zullo Investimenti Srl, a recently incorporated holding company which, as of the date of this report, remains inactive. Ownership of Zullo Investimenti S.r.l. is equally held by shareholders Walter Zullo and Michele Zullo, the latter also serving as the Company's Sole Director.
Between late 2025 and 2026, the global energy and economic environment has been characterized by heightened uncertainty. Worldwide electricity demand continues to expand, supported by the rapid deployment of renewable energy capacity, particularly solar photovoltaic and wind power, while fossil fuels continue to play a significant role in the global energy mix.
Geopolitical tensions in the Middle East, particularly those involving Iran and the Strait of Hormuz, have increased volatility in global oil and natural gas markets, contributing to higher inflationary pressures and influencing monetary policy decisions across major economies. In Italy, despite continued growth in renewable electricity generation, the country’s significant dependence on natural gas continues to support elevated energy prices, prompting the Government to postpone the planned closure of certain coal-fired power plants in order to safeguard security of supply.
From a macroeconomic perspective, Italy's economy continued to expand at a moderate pace during the first months of 2026, driven primarily by the services sector, while manufacturing activity remained under pressure due to higher energy costs and weak external demand. Household consumption and private investment recorded only modest growth amid persistent uncertainty and reduced purchasing power. According to the latest projections of the Bank of Italy, real GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. Nevertheless, the outlook remains subject to significant downside risks associated with geopolitical developments, energy commodity prices, and international trade conditions.
Sensitivity Analysis
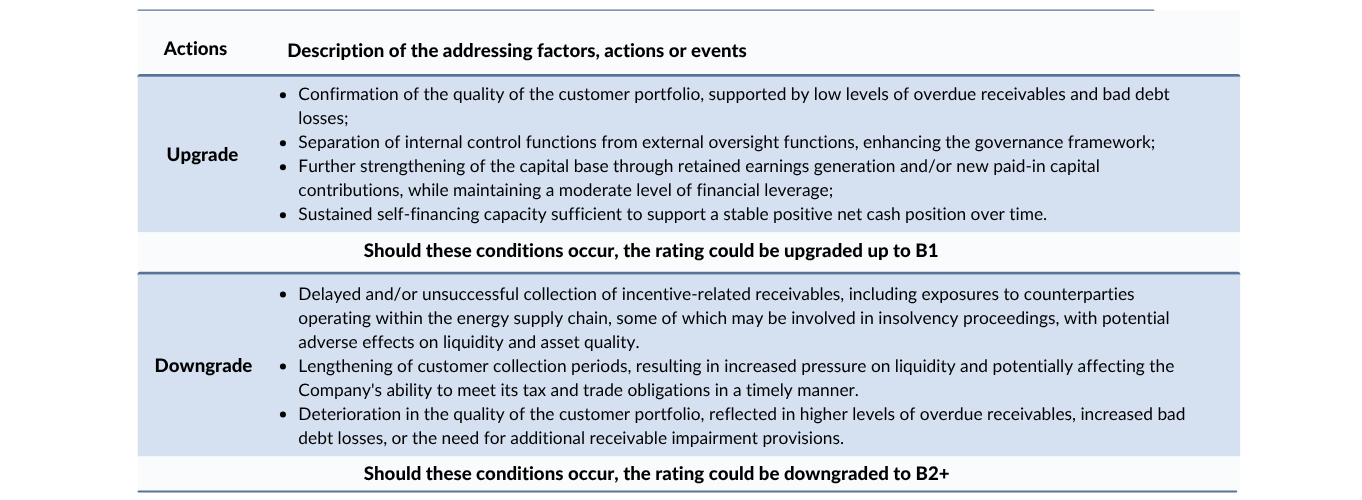
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company did not purchased any ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Azzurra Nicchi, Rating Analyst
azzurra.nicchi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com