Solicited Corporate Credit Rating for NEWATT S.R.L.: A3+ (Affirm)
modefinance published the Solicited Corporate Credit Rating of NEWATT S.R.L. on the website and the rating assigned to the entity is A3+ (Affirm). The analysis revealed Company’s capacity to meet its commitment on financial obligations is strong.
NEWATT S.R.L. (hereinafter also referred to as "the Company"), was established in 2015 and operates in the energy sector, where it acts as a supply-chain partner for small reseller operators. The Company’s management is pursuing a disciplined growth strategy, capitalizing on market opportunities that have, to date, contributed to the creation of a robust Group. The Company leverages an innovative algorithmic approach and AI-powered software, supplying energy directly to the meter and ensuring efficient supply chain management. Over the 2025–2026 period, the Group completed a reorganization process aimed at supporting its next growth cycle through organizational integration, the definition of roles and responsibilities, and the establishment of a Leadership Team. The completion of an integrated Group-wide platform is also underway. Future development will continue to focus on three strategic assets: people, IT systems, and risk management.
Key Rating Assumptions
NEWATT S.R.L. maintained a fully adequate economic and financial position in 2025. Overall performance was characterized by strong profitability levels (ROE = 34.45%), a solid capital structure (leverage = 1.17x), and a sound financial balance (current ratio = 1.72x). The Company also maintained a net cash position, with net financial debt amounting to negative €14.13 million.
In 2025, NEWATT recorded a significant increase in cash and cash equivalents, primarily supported by positive operating cash flow (€8.23 million), driven by internally generated funds and efficient working capital management. This was further supplemented by divestment proceeds related to the disposal of equity investments, which contributed an additional €4.24 million in cash inflows. Financing cash flow also benefited from the raising of new debt and a capital increase.
The governance and control system remains adequate, with a Board of Directors that includes NEWATT shareholders, supported by a sole statutory auditor. In July 2024, Dr. Massimiliano Carpegna joined the board and was appointed Chief Executive Officer with broad managerial and commercial authority, bringing twenty-five years of industry experience. The Company continues to operate without an external supervisory body. The Group’s structure is continuously evolving and expanding, though the relationships among its various companies are clearly defined.
Compared with the sector peer group, Newatt shows a substantial and growing scale, supported by the increase in business volumes, positioning the Group among the most significant operators in the sector at the national level. Profitability remains at adequate levels, and its solvency position is above the peer median, thanks to a balanced mix of funding sources and sustainable financial leverage. The peer group as a whole also shows a generally positive performance, with a balanced capital structure and financial leverage gradually improving. The financial position is sound, and the economic performance is noteworthy.
Between late 2025 and 2026, the energy and economic environment has been marked by a high degree of uncertainty. Globally, electricity demand continues to grow, while renewable energy capacity, particularly solar and wind power, keeps expanding. At the same time, fossil fuels continue to play a central role in the global energy mix. Geopolitical tensions in the Middle East, particularly those involving Iran and the Strait of Hormuz, have increased volatility in oil and natural gas prices, generating inflationary pressures and influencing monetary policy decisions. In Italy, despite the increase in renewable energy generation, the country's significant reliance on natural gas continues to support elevated energy prices. As a result, the Government has postponed the phase-out of certain coal-fired power plants in order to safeguard security of supply.
From an economic perspective, Italy's growth remained moderate in the first months of 2026, driven primarily by the services sector, while manufacturing activity was affected by rising energy costs and weaker external demand. Household consumption and corporate investment continued to expand only gradually, constrained by persistent uncertainty and the erosion of purchasing power. According to the Bank of Italy's projections, GDP growth is expected to reach 0.5% in both 2026 and 2027, accelerating to 0.8% in 2028. Nevertheless, the outlook remains subject to significant downside risks stemming from geopolitical developments and energy market dynamics.
Sensitivity Analysis
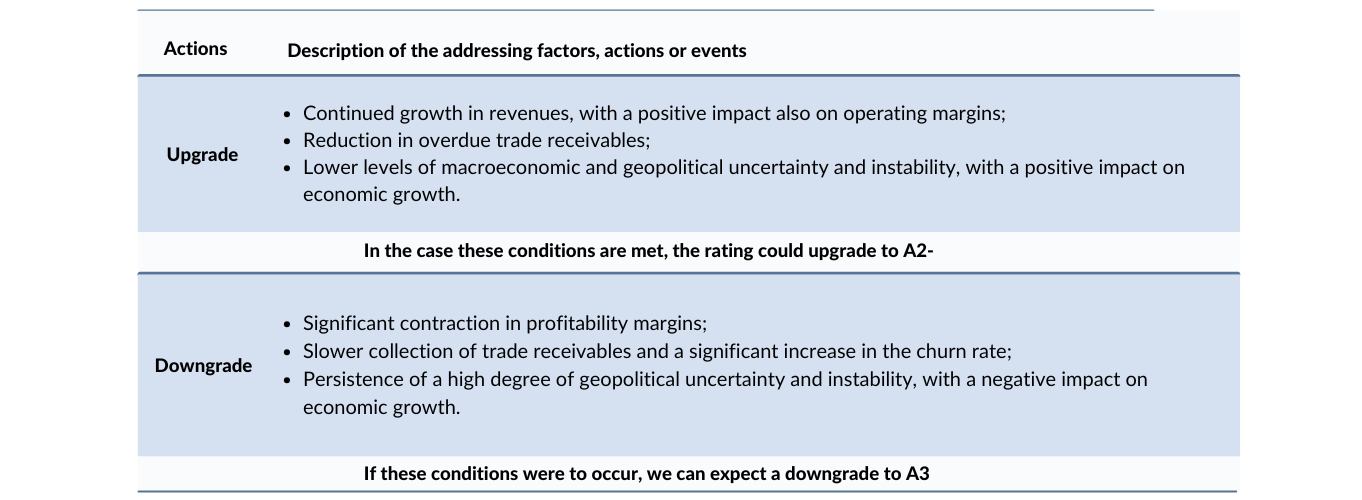
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated entity buys ancillary services provided by modefinance (credit scores). No conflit of interest have been found.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn. The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com