Solicited Corporate Credit Rating for OPTIMA ITALIA S.P.A.: B1 (Affirm)
Modefinance published the Solicited Corporate Credit Rating of OPTIMA ITALIA S.P.A. on the website and the rating assigned to the entity is B1 (Affirm). The analysis highlights that the company has an average capability to fulfil its financial obligations, demonstrating the capacity to withstand adverse economic scenarios.
OPTIMA ITALIA S.P.A. (hereinafter also referred to as “the Company”) is an Italian multi-utility company headquartered in Naples, offering an integrated portfolio of electricity, natural gas, fixed and mobile telecommunications services, as well as value-added services. The Company was founded in 1999 by Danilo Caruso and Alessio Matrone, initially operating in the telecommunications and internet services sector. Over time, it expanded its business scope to include the sale of electricity and natural gas, evolving from a telecommunications operator into an integrated multi-utility provider. Today, the Company serves residential, business and public administration customers through a proprietary sales network supported by dealers and digital channels, and operates throughout Italy.
Key Rating Assumptions
The Company closed FY2025 with revenues of EUR 430.7 million, up 16.9% year-on-year, driven by the expansion of its customer base and higher electricity and natural gas volumes. Gross margin reached EUR 125.2 million (+9.3%), while EBITDA amounted to EUR 72.7 million, substantially in line with the previous year. Net profit stood at EUR 3.8 million. During the year, the reverse merger with the parent company strengthened the Company's capital structure, with shareholders’ equity increasing from EUR 20.5 million to EUR 45.5 million, and total assets rising from EUR 154.3 million to EUR 223.5 million. The Net Financial Position (NFP) increased to EUR 38.7 million, mainly as a result of the purchase of treasury shares, while the debt structure was rebalanced through a greater proportion of medium-to-long-term liabilities. From a liquidity perspective, OPTIMA ITALIA S.P.A. generated operating cash flows of EUR 72.7 million and closed the year with cash and cash equivalents of EUR 28.6 million (+56.9%). Investments amounting to EUR 56.7 million were primarily related to intangible assets and customer acquisition costs. Leverage improved from 6.52x to 3.91x, confirming the strengthening of the Company's financial structure.
OPTIMA ITALIA S.P.A. is managed by a Board of Directors, supported by a Board of Statutory Auditors and an independent audit firm. The Organisational Model pursuant to Legislative Decree 231/2001 is overseen by a collegiate Supervisory Body. The ownership reorganization was completed in 2025 through the merger by incorporation of the parent company, Optima Holding S.P.A., whose shares were allocated to its shareholders, Mr. Danilo Caruso and Mr. Alessio Matrone, and to their respective trusts. The Company subsequently acquired a 20% stake from the Alpha Private Equity fund, through Optiworld S.A R.L., and holds these shares as treasury shares. In February 2026, the shareholders and trusts contributed their interests to LA Holding S.R.L., which now holds 80% of the share capital.
Compared with its peer group, the Company remains among the largest operators in the sector, supported by continued growth in revenues and customer base. Solvency improved significantly following the strengthening of shareholders’ equity in 2025, although leverage remains above the sector median. Profitability deteriorated compared with 2024, with ROE declining as a result of higher shareholders’ equity and lower net profit. The peer group continues to display overall adequate capitalization and leverage levels, while profitability remained broadly stable over the 2024-2025 period.
In 2026, the energy market is characterised by growing electricity demand and the strong expansion of renewable energy sources, particularly solar and wind power. However, fossil fuels continue to play a central role, while geopolitical tensions involving Iran and restrictions affecting the Strait of Hormuz have increased energy price volatility and inflationary pressures. In Italy, renewable sources account for 41% of electricity consumption, but the country's dependence on natural gas continues to keep energy prices elevated and has led the Government to postpone the closure of certain coal-fired power plants in order to safeguard energy security. From a macroeconomic perspective, the Italian economy recorded weak growth in the first quarter of 2026, supported mainly by the services sector, while manufacturing, consumption and investment were affected by higher energy costs and international uncertainty. According to the latest forecasts by Bank of Italy, Italian GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating moderately to 0.8% in 2028.
Sensitivity Analysis
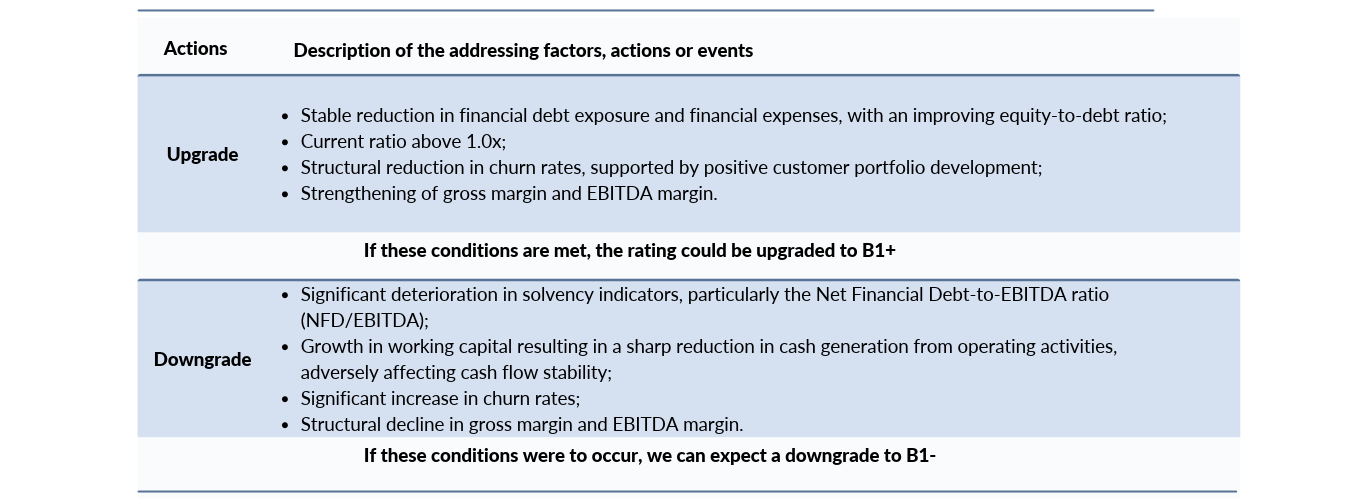
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated entity is not a buyer of ancillary services provided by modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Andrea Pausa, Rating Process Analyst
a.pausa@teamsystem.com