Solicited Corporate Credit Rating for RICCI S.P.A.: B1- (First issuance)
Modefinance published the Solicited Corporate Credit Rating of RICCI S.P.A. on the website and the rating assigned to the entity is B1- (First Issuance). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
Ricci S.P.A. (hereinafter also referred to as "the Company”) has been active for forty years in the sectors of new construction, renovation, and the restoration of proprieties of historic and artistic value. The Company primarily operates as a general contractor, assuming overall responsibility for project execution and directly overseeing planning, coordination, quality control, safety, and client relationship management. Its operations are structured across three business segments: hospitality, culture & wellness; commercial and industrial; and residential and real estate. Its client base consists mainly of real estate funds, asset management companies (SGRs), and hotel groups. Since 2024, the Company has also progressively strengthened its presence in the public procurement market.
Key Rating Assumptions
In 2025, Ricci S.P.A. reported a production value of EUR 69.3 million, down 14.2% compared with 2024. EBITDA amounted to EUR 2.8 million, with an EBITDA margin of 4.0%, remaining substantially in line with the previous year. Shareholders’ equity increased to EUR 12.5 million, while total assets reached EUR 82.2 million following the acquisition of a stake in G.T. 2 S.R.L. The Net Financial Position (NFP) amounted to EUR 19.4 million and was also influenced by the use of factoring and trade receivables advance facilities supporting working capital requirements. The Company also reported an order backlog of approximately EUR 117 million as at 30 June 2026, equal to around 1.8 times 2025 revenues, providing good visibility on future business activity. From a financial standpoint, operating activities generated EUR 8.2 million in cash, enabling a significant strengthening of liquidity, which increased to EUR 6.4 million at year-end from EUR 3.3 million in the previous year. Available evidence as at 31 July 2026 shows performance broadly in line with the objectives set out in the 2026-2028 business plan, with revenues amounting to EUR 47.5 million in the first seven months of the year and NFP reduced to EUR 12.1 million. The plan envisages moderate growth in volumes and a gradual improvement in profitability, despite an increase in financing requirements arising from working capital absorption associated with business development.
Ricci S.P.A. has a structured governance and control framework. Management is entrusted to a six-member Board of Directors, oversight functions are performed by a Board of Statutory Auditors, and statutory auditing is carried out by a leading audit firm. The Company has also adopted an Organisational, Management and Control model pursuant to Italian Legislative Decree 231/2001, which has been publicly certified. The Company is wholly owned by Mr. Mario Ricci, Chairman of the Board of Directors. The Group includes the subsidiaries G.T. 2 S.R.L. (100%, acquired in 2025), Innovazioni Abitative S.R.L. (100%), and M.T. Ricci S.R.L. (66.67%), the associate Mamiris S.R.L. (45%), and a majority stake in Il Castello Società Consortile a R.L. (51%).
Compared with its industry peer group, the Company stands out for its significantly larger operating scale, while profitability and solvency indicators remain below sector medians. The financial structure remains more reliant on third-party funding, and operating margins are below benchmark levels. Overall, the sector continues to display adequate solvency and liquidity levels, with profitability stabilising at satisfactory levels following the decline from the peaks recorded in 2023.
The construction sector is currently experiencing a normalisation phase following the expansionary cycle driven by tax incentives and extraordinary building refurbishment schemes. The gradual slowdown in private demand has been largely offset by growth in public works related to the National Recovery and Resilience Plan (PNRR), which continues to support production levels across the industry. Short-term prospects remain favourable thanks to the ongoing implementation of planned infrastructure investments, although the sector continues to operate in a more selective environment characterised by increased pressure on margins and less favourable financing conditions than in recent years.
From a macroeconomic perspective, Italian economic growth remained moderate in the first months of 2026, supported mainly by the services sector, while manufacturing has been affected by rising energy costs and weak external demand. Household consumption and investment have expanded only gradually due to persistent uncertainty and the erosion of purchasing power. According to the latest projections by the Bank of Italy, GDP is expected to grow by 0.5% in both 2026 and 2027, accelerating to 0.8% in 2028, although significant risks remain related to geopolitical developments and the evolution of energy markets.
Sensitivity Analysis
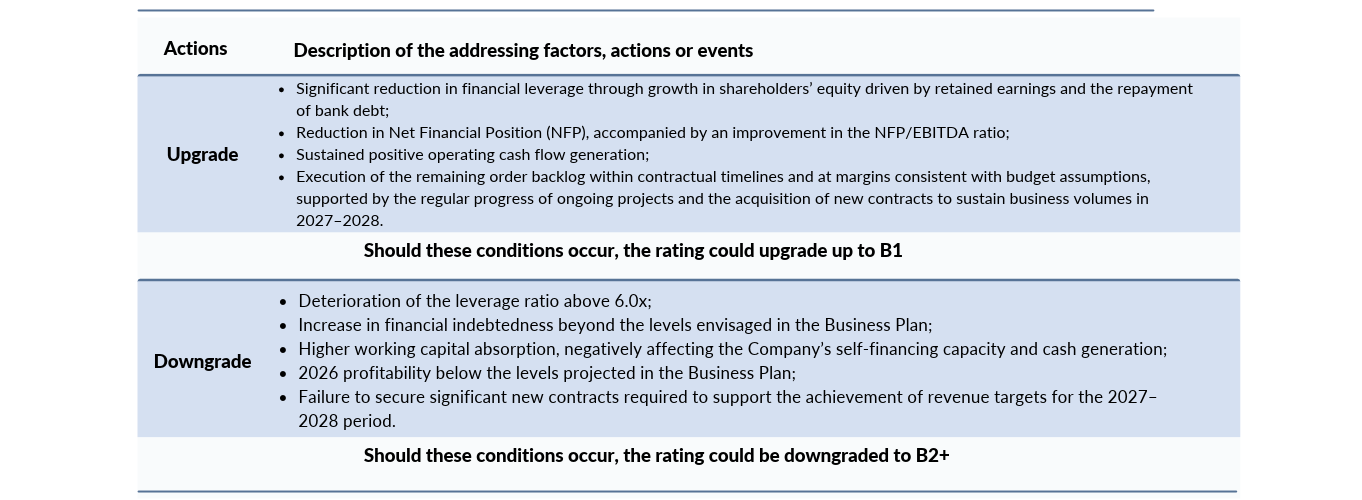
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company has not purchased ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com