Solicited Corporate Credit Rating for RONCADIN S.P.A. SB: B1+ (Affirm)
modefinance published the Solicited Corporate Credit Rating of RONCADIN S.P.A. SB on the website and the rating assigned to the entity is B1+ (Affirm). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
RONCADIN S.P.A. SB (hereinafter also referred to as “the Company") is an Italian company located in Meduno (PN) that was founded in 1992. It specializes in producing high-quality frozen pizzas for large-scale distribution, operating both under its own brand and as a private label. In 2021, the Company became a Benefit Corporation, reinforcing its commitment to sustainable and responsible development. By 2024, it achieved the prestigious B Corp certification, which recognizes companies that meet the highest standards of environmental, social, and governance performance. Roncadin has established a strong international footprint, with a solid presence across key foreign markets and exports accounting for the predominant share of its revenues. The investments undertaken in recent years reflect the Group’s commitment to further strengthening its global positioning and supporting its future growth prospects.
Key Rating Assumptions
Roncadin closed 2025 with growing results, confirming the effectiveness of its development strategy. Consolidated revenues reached €250.6 million, up 25.1% compared to 2024, while EBITDA increased to €21.6 million, confirming the Group’s ability to combine business expansion with the maintenance of a satisfactory level of profitability. The Group continues to benefit from a solid financial and capital structure, supported by a sound ability to generate operating cash flows. Net Financial Position increased during the year as a result of the significant investment plan undertaken to support growth and strengthen production capacity; nevertheless, leverage remains balanced and consistent with the Group’s size and cash generation capability. The strategic investments launched in recent years are aimed at consolidating Roncadin’s competitive positioning and supporting its long-term growth prospects. Despite the negative impact of foreign exchange dynamics on the bottom line, the Group closed the year with a consolidated net profit of €4.3 million, confirming the resilience of its business model and its ability to deliver positive results even in an unfavorable currency environment.
The Company benefits from a solid governance and control framework. Management is entrusted to a suitably structured Board of Directors, while oversight and statutory audit activities are carried out respectively by the Board of Statutory Auditors and a leading audit firm. Since 2011, Roncadin has also adopted an Organizational, Management and Control Model pursuant to Italian Legislative Decree 231/2001. Controlled by the holding company Kanada S.p.A., Roncadin heads a group that includes Ronca Lab S.r.l., its subsidiary Antica Pizzeria S.r.l., and the U.S. business platform headed by Roncadin USA Holding Corp., through which the Group oversees its manufacturing and real estate activities in the United States.
Compared to its industry peer group, the Roncadin Group demonstrates strong scale, ranking among the largest companies in terms of revenues. Solvency indicators are broadly in line with industry benchmarks, while profitability remains below the median levels observed within the reference peer group. Over the 2022-2025 period, the peer group recorded an overall balanced economic and financial profile. Solvency indicators remained at adequate levels, while profitability, following the significant improvement recorded in 2023, subsequently stabilized at positive and sustainable levels.
In 2026, the international macroeconomic environment remains broadly supportive, albeit with differing trends across major geographic areas. Europe continues to experience moderate growth, while the United States shows stronger economic momentum. Nevertheless, risks related to geopolitical tensions and the evolution of the global economic and financial environment persist.
Sensitivity Analysis
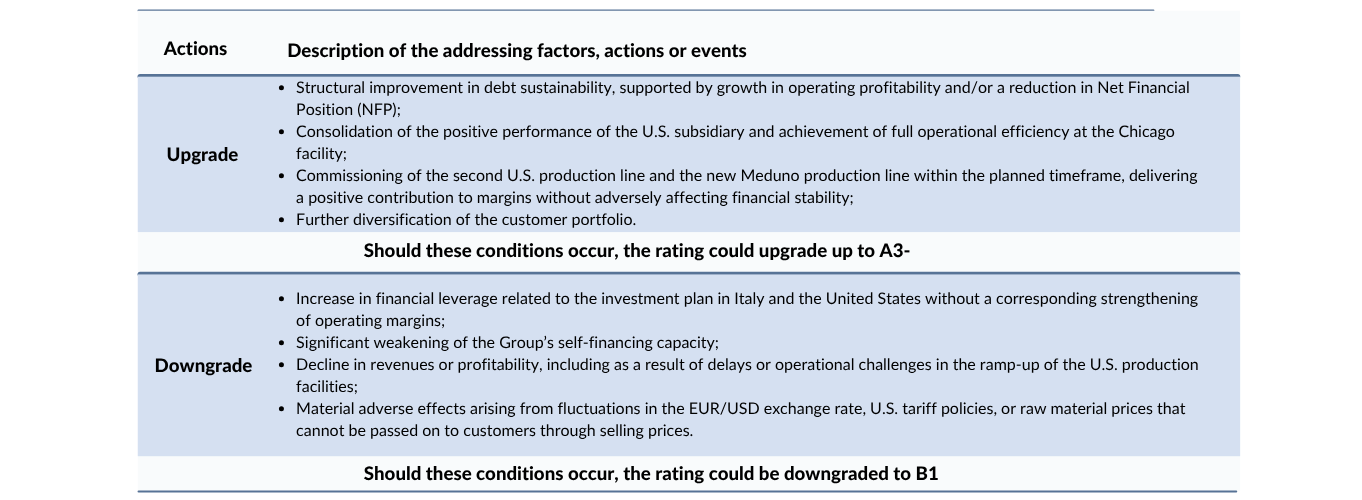
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company has not purchased ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com