Solicited Corporate Credit Rating for STAR7 S.P.A.: B1+ (Affirm)
Modefinance published the Solicited Corporate Credit Rating of STAR7 S.P.A. on the website and the rating assigned to the entity is B1+ (Affirm). The analysis highlights that the company has an adequate economic and financial situation, demonstrating an average capability to withstand adverse economic conditions in the medium and long term.
STAR7 S.P.A. (hereinafter also referred to as “the Group”) has evolved from an operator providing translation and printing services into an integrated provider of product information management solutions. The Group provides product and process engineering support, develops and manages technical and marketing content, offers translation and printing services, and delivers immersive 3D solutions for training and communication.
In November 2025, the subsidiary STAR7 LLC acquired a 20% stake in Almon Inc., a US company operating in specialty vehicles, agricultural machinery, aerospace and defense, with options that could lead to full control. In July 2026, Argos took control of the Group, which subsequently changed its debt structure. The Group entered into new medium- to long-term credit facilities of €54 million and repaid existing bonds and bank debts.
Key Rating Assumptions
In 2025, consolidated revenue was €116.1 million (-3.1% YoY), EBITDA (MOL) was €18.5 million (+€0.5 million YoY), and EBITDA margin grew at 16% (+1 percentage point). These results reflect, on the one hand, the depreciation of foreign currencies, notably the Brazilian real and the US dollar against the euro, and, on the other, the reorganization of the Engineering and Global Content lines, including the closing of less profitable contracts. Despite significant amortization, mainly related to goodwill on Localeyes and STAR7 Engenharia, arising from the application of Italian GAAP (OIC), the Group posted a net profit of €3.2 million and an adequate return on equity. The improvement in leverage and debt sustainability indicators, with Net debt to EBITDA at 1.15x at year-end, confirms an adequate capacity to meet financial commitments. Following the delisting and the change of control, Management did not provide 2026 guidance, which is considered confidential. The development strategy remains focused on scaling growth, including through M&A in markets and segments with favourable prospects.
In 2025, STAR7 S.p.A. maintained liquidity of €24.4 million (€25.5 million at end-2024), supported by operating cash generation of €15.4 million from results and efficient working capital management. Cash flows fully funded investments in the period, mainly the acquisition of the Engineering business of the Brazilian company C.A.A.R. DO BRASIL and enabled the repayment of €12.6 million of maturing loans. Cash and cash equivalents declined modestly year-on-year (-€0.9 million).
In July 2026, Argos acquired control of STAR7 through 7BidCo S.p.A. The transaction involved new debt at STAR7 to finance an extraordinary dividend of €20 million, partly invested by former shareholders in STARGALAXY 7 S.A., the indirect parent of 7BidCo. The Company delisted its shares from Euronext Growth Milan on August 12, 2026. The most significant Group investments are Localeyes, acquired in 2021 and active in the Global Content and Product Knowledge business lines, and the Brazilian subsidiaries Star7 Engenharia e Consultoria Técnica Ltda (formerly CAAR do Brasil, acquired in 2025) and Star Comunicação e Serviços Ltda, operating in the Engineering and Printing/Product Knowledge segments.
The Group has a structured governance framework with several oversight levels: a Board of Directors supported by a Board of Statutory Auditors, an external audit firm responsible for the statutory audit, and a collegial Supervisory Body established under Legislative Decree 231/2001. The new Board reconfirmed Lorenzo Mondo as Chief Executive Officer, ensuring continuity in implementing a growth strategy focused on technological innovation and integration of Artificial Intelligence into the Group’s services and processes.
STAR7 remains among the leading players in the reference sector within a peer group with revenues between €50 million and €500 million. In 2025, its solvency profile strengthened further and aligned with the sector median. Regarding liquidity and profitability, the company’s position remained strong relative to the reference peer group, even though the latter was affected by significant goodwill amortization linked to acquisitions made in previous years. Excluding these components, profitability would be at significantly stronger levels. The peer group analyzed shows an overall sufficient economic and financial profile, as confirmed by the majority of companies falling into class 6 of the MORE Score. Although sector profitability has deteriorated reaching inadequate levels, the financial structure remains balanced, and sector solvency indicators improved compared with the previous year, remaining at sufficient levels.
In the first quarter of 2026, the Italian economy continued to expand at a moderate pace despite heightened geopolitical uncertainty. Economic activity continued to grow, supported by the services sector, partly driven by the temporary Winter Olympics games; in contrast, the manufacturing sector slowed down due to higher energy costs and weaker foreign demand. Household consumption grew modestly, constrained by weakening consumer confidence and the erosion of purchasing power resulting from rising energy prices. Investment activity also slowed, reflecting uncertainty about the macroeconomic outlook and the gradual fading of incentives in the residential sector. According to the latest Bank of Italy projections, GDP growth is expected to reach 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. Over the medium term, economic activity should benefit from easing inflationary pressures and a recovery in domestic demand; however, near-term prospects remain exposed to downside risks related to geopolitical tensions in the Middle East, developments in energy markets and international trade dynamics. In contrast, the United States continues to demonstrate stronger economic momentum, with growth expected to exceed 2%, supported by a resilient labour market, strong innovation capacity and sustained private investment. Nevertheless, both economies remain exposed to common risks, particularly those associated with geopolitical developments, inflation trends and the future path of monetary policy.
Sensitivity Analysis
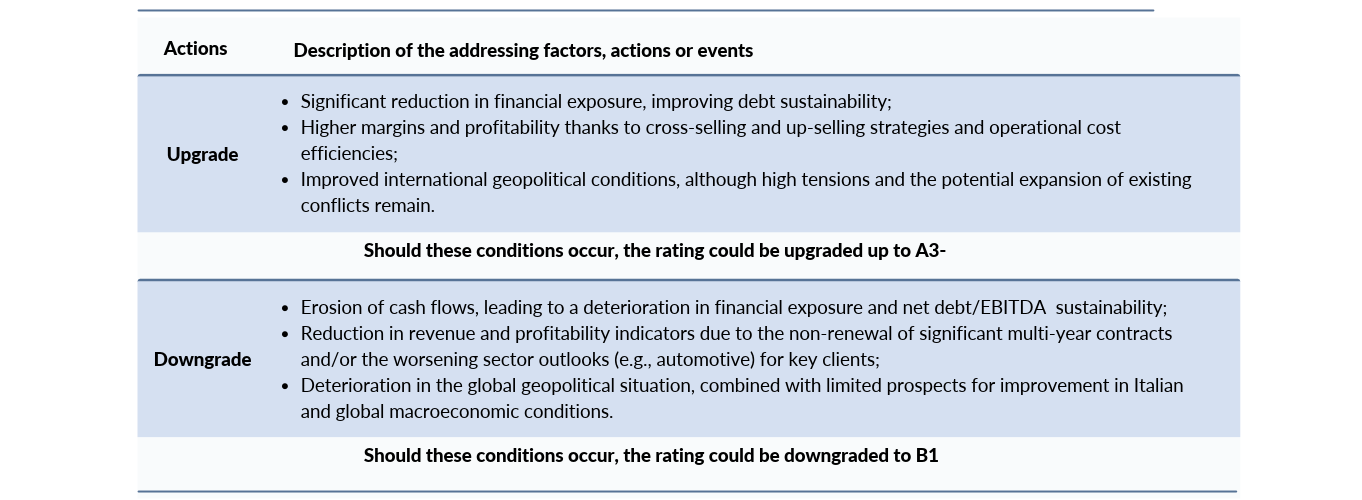
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated entity is not a buyer of ancillary services provided by modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Carmela Santomarco, Rating Analyst
carmela.santomarco@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com