Solicited Corporate Credit Rating for START S.R.L. SB: B1 (Affirm)
modefinance published the Solicited Corporate Credit Rating of START S.R.L. - SB on the website and the rating assigned to the entity is B1 (Affirm). The analysis revealed that the company has an adequate economic and financial situation, capable of facing adverse economic conditions in the medium and long term.
START S.r.l. – Benefit Corporation (hereinafter also “the Company”) is an energy utility active in the sale of electricity and gas. Founded in 2012, the Company transitioned in 2021 from a commercial agency to a direct energy supplier through the launch of the Rec Energy brand. Growth in recent years has been supported by a strategy focused on simple offerings, streamlined processes and the acquisition of qualified customers. In 2023, the Company attained Benefit Corporation status, integrating ESG objectives into its governance framework and promoting more sustainable energy consumption. Between 2024 and 2025, the Company strengthened its operating model by placing greater emphasis on the direct procurement of energy, generating benefits in terms of both profitability and market competitiveness. At the same time, a multi-brand strategy was launched through the development of the CAE Energia, Plug Energy, and CAF Energia brands. In 2025, the Company also began structuring a corporate group organized by sales channels and customer segments, with Start expected to assume the role of central purchasing entity for all subsidiaries once they become fully operational. This model is intended to generate economies of scale, optimize financial management, and ensure greater consistency across processes and governance practices throughout the Group. In 2026, the project further evolved with the addition of new companies and the establishment of Servix Hub S.r.l., a shared services center responsible for providing administrative, accounting, and financial services to the Group. The initiative is aimed at supporting future growth and enhancing the scalability and efficiency of the Group’s organizational model.
Key Rating Assumptions
START S.r.l. – Benefit Corporation confirms a sound financial and economic position. In 2025, the Company recorded a significant increase in sales revenues, rising from €23.9 million to €66.9 million. This growth translated into a substantial strengthening of operating profitability, with EBITDA increasing to €10.23 million from €2.28 million, and net profit reaching €6.77 million compared to €1.42 million in the previous year. The management of current assets and liabilities remains balanced, as reflected by a current ratio of 1.24x, while the Company's capital structure is also considered sound, with a leverage ratio of 1.77x. Financial indebtedness appears fully sustainable, with the Company reporting a net cash position (NFP) of €10.99 million. Cash and cash equivalents increased during the year, supported by the Company's ability to generate cash from operating activities, driven by higher profitability and a positive contribution from working capital management. Cash flows generated by core operations fully funded the investments carried out during the period, which were primarily related to the acquisition of equity interests in subsidiaries. The increase in liquidity was also supported by financing activities, reflecting both the drawndown of new debt facilities and a corporate reorganization transaction involving the contribution of a business unit to a dedicated company providing administrative, accounting, financial, and management support services. This transaction strengthened the Company's equity base through the recognition of the investment among financial fixed assets and the recording of a specific reserve within shareholders' equity. Going forward, particular attention should be paid to the trend in trade receivables and the management of overdue balances in order to ensure their timely collection. The trend in trade receivables and the management of overdue balances should be monitored to ensure timely collection.
The Company has a lean corporate structure, with ownership ultimately attributable to Mr. Andrea Diffido, who exercises control through an S.r.l. holding a 90% stake in START. The remaining 10% is held by Mr. Aldo Broegg through an S.r.l. wholly owned by him. Mr. Diffido also serves as START’s Sole Director. In 2026, an independent audit firm was appointed. Over the past year, the Group expanded through the addition of four new subsidiaries.
START S.r.l. has a solid size positioning, supported by the significant growth in turnover. The Company also confirms good profitability, underpinned by robust returns on invested capital and equity. From a solvency perspective, the strengthening of the capital base has improved the Company’s financial position, with a progressive reduction in the leverage ratio towards more balanced levels. The peer group shows a progressive strengthening of its financial structure, with a reduction in both overall and financial leverage, consistent with lower reliance on third-party capital. Liquidity indicators remain at satisfactory levels, confirming an adequate capacity to meet current obligations. Profitability is broadly stable, with ROE and ROCE remaining positive and indicative of a sound capacity to generate returns.
Between late 2025 and 2026, the energy and economic environment have been characterized by significant uncertainty. At a global level, electricity demand continues to increase, and renewable energy capacity continues to expand, particularly in solar photovoltaic and wind power, while fossil fuels retain a central role in the energy mix. Geopolitical tensions in the Middle East, particularly those involving Iran and the Strait of Hormuz, have contributed to oil and gas price volatility, with inflationary effects and implications for monetary policy.
In Italy, despite the increase in renewable energy generation, the country’s continued strong dependence on natural gas remains a factor supporting elevated energy prices. This has led the Government to postpone the closure of certain coal-fired power plants in order to safeguard security of supply. From an economic standpoint, in the first months of 2026, Italian economic growth has remained moderate, supported mainly by the services sector, while manufacturing has been affected by higher energy costs and weak external demand. Consumption and investment are growing slowly due to uncertainty and the erosion of purchasing power. The Bank of Italy forecasts GDP growth of 0.5% in both 2026 and 2027, accelerating to 0.8% in 2028, although significant risks remain linked to developments in the geopolitical environment and energy markets.
Sensitivity Analysis
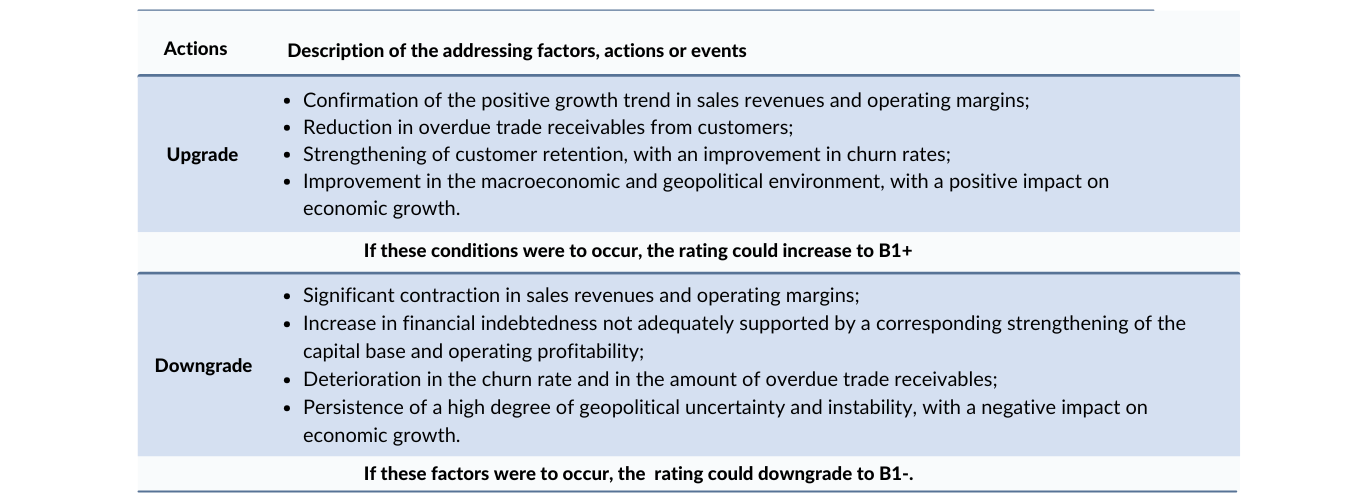
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company does not purchase ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn. The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com