Solicited Corporate Credit Rating for TASK S.R.L.: B1+ (Affirm)
modefinance published the Solicited Corporate Credit Rating of TASK S.R.L. on the website and the rating assigned to the entity is B1+ (Affirm). The analysis highlights that the company maintained an adequate economic and financial profile, demonstrating the capacity to withstand adverse economic conditions over the medium to long term.
TASK (hereinafter also referred to as "the Company"), originally established as a distributor of industrial components, has evolved into a more sophisticated business integrating technical expertise, advanced application consulting and design capabilities, moving beyond the traditional distribution model. In the industrial automation sector, the Company stands out for its distinctive positioning, supported by a broad technology offering ranging from inverters to vision systems, as well as cross-functional expertise enabling it to develop precise, high-value solutions. The in-house technical team effectively supports the sales force, while partnerships with international manufacturers further strengthen the Company’s advisory role. TASK operates as a cross-functional strategic partner, offering both general-purpose products and advanced automation and identification solutions. In recent years, the Company has faced exceptional market dynamics and the impact of its main customer; however, the portfolio managed by the sales team resumed growth in 2025 almost entirely offsetting the contraction in business with the aforementioned customer. At June 2026 the portfolio managed by the sales team increased, reaching its highest level over the last three financial years and confirming the strengthening of the Company’s in-house commercial capabilities. Accordingly, 2026 is shaping up as a year of consolidation and sustainable growth, with revenues expected to be broadly in line with, or slightly above, 2025 levels. More recently, registration with MEPA has opened up new opportunities in the Italian Public Administration market. The Company is ISO 9001:2015 certified (IQNET and CSQ-IMQ). Finally, it should be noted that the Company prepares and publishes a Sustainability Report, demonstrating a structured commitment to ESG matters.
Key Rating Assumptions
TASK S.r.l. also confirmed an adequate financial position in 2025, with no significant areas of concern. The Company is characterized by a balanced capital structure and limited, sustainable financial indebtedness, with a net cash position. The absence of anomalies in the Central Credit Register and the Company’s regular debt-servicing capacity have enabled it to maintain a high level of creditworthiness with lending institutions. This position translates into easy access to credit and favorable financing conditions, to support operations and investments. The Company also maintains an appropriate balance between current assets and current liabilities. In 2025, the Company further strengthened its liquidity position. This increase was attributable to the positive operating cash flow, which generated sufficient resources to fund investments and repay part of its financial debt. Operating performance benefited both from internally generated funds and from more efficient management of net working capital. Overall, cash flow dynamics improved and strengthened compared with the previous financial year, highlighting a balanced financial position and efficient management of financial resources. In 2025, financial performance remained broadly stable, with revenues of €7.4 million (+2% YoY), representing a fully adequate level in terms of both operating margin and net margin. A more pronounced recovery in sales revenues and a strengthening of margins are expected in 2026.
The Company has a lean corporate structure, with control ultimately held by Mr. Donato Crisostomo, Chairman of the Board of Directors and General Manager, who is also responsible for the sales function. He is supported by two minority shareholders, including Mr. Remo Uberti, a member of the Board of Directors and responsible for the administrative function. The Company does not hold equity interests in other companies. No Board of Statutory Auditors is in place, as its appointment is not mandatory, while a sole statutory auditor has been appointed. The Company has a well-structured and functional organizational setup, with direct oversight by General Management of the main operating and governance areas. During the latest financial year, the organization was further strengthened through new hires in the IT function, aimed at supporting digitalization and cybersecurity oversight. Alberto Crisostomo was also appointed to the Strategy and Analysis function, leveraging his experience in the financial sector. The new resource will also contribute to the oversight and development of ESG matters, further strengthening the Company’s strategic planning capabilities.
Task S.r.l. confirms an adequate positioning within its sector peer group in terms of size and solvency. Profitability is below the 50th percentile of the sample, although it remains adequate when assessed on a stand-alone basis. The sector peer group analyzed shows an improvement in solvency between 2022 and 2025, with leverage remaining at a balanced level and financial leverage remaining very limited. Liquidity across the sample remained adequate throughout the period, with indicators above 1.0x and showing an upward trend. Profitability ratios remained adequate and broadly stable.
The industrial automation sector recorded a moderate recovery in 2025 (+4%) following the sharp decline experienced in 2024 (-27%). Demand is driven primarily by machine builders, system integrators and manufacturing companies. Distribution continues to play a significant role and is increasingly focused on value-added services. Key growth drivers include digitalization, Industrial IoT, robotics, machine vision and industrial AI, also supported by public incentives and the European Chips Act. Overall, the market is currently in a recovery phase, with prospects for moderate growth and substantial continuity in 2026.
In the first months of 2026, the Italian economy continued to grow at a modest pace, against an international backdrop characterized by a marked increase in geopolitical uncertainty. Economic activity was supported mainly by the services sector, also benefiting from the temporary boost associated with the Winter Olympic Games, while manufacturing showed signs of a slowdown due to rising energy costs and weak external demand. Household consumption increased moderately, affected by weaker confidence and the erosion of purchasing power resulting from higher energy prices. Investment growth also slowed, with only a limited positive contribution amid uncertainty surrounding the macroeconomic environment and the gradual phase-out of incentives in the residential sector. According to the latest projections published by the Bank of Italy, Italian GDP is expected to grow by 0.5% in both 2026 and 2027, before accelerating to 0.8% in 2028. In the medium term, economic activity is expected to be supported by the gradual easing of inflationary pressures and the recovery in domestic demand. In the short term, however, the outlook remains exposed to downside risks related to developments in the conflict in the Middle East, energy commodity prices and international trade.
Sensitivity Analysis
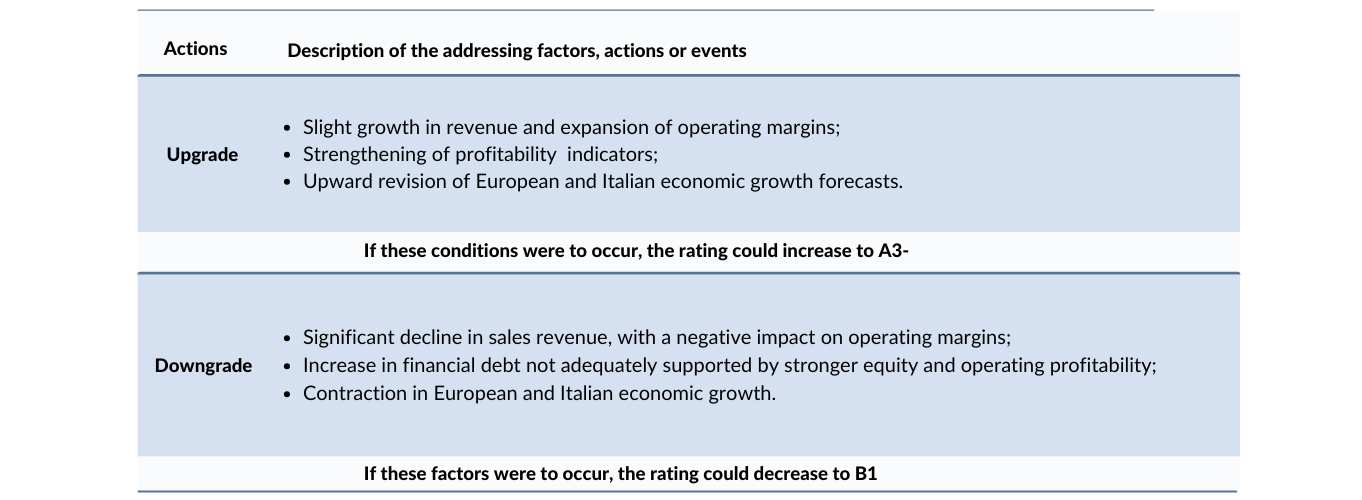
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation. No amendments were applied after the notification process. The rated company purchased ancillary services from modefinance (preliminary rating). Modefinance guarantees that this purchase of ancillary activities does not constitute any conflict of interest.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn. The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Elisa Graffi, Rating Analyst
elisa.graffi@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com