Solicited Corporate Credit Rating for UNION S.R.L.: B1 (Upgrade)
modefinance published the Solicited Corporate Credit Rating of UNION S.R.L. on the website and the rating assigned to the entity is B1 (Upgrade). The analysis highlights that the company has an adequate financial position, demonstrating the capacity to withstand adverse economic conditions in the medium and long term.
Established in 2017, UNION S.R.L. (hereinafter also referred to as “the Company") is an Italian energy company active in the supply of electricity and natural gas within the liberalized energy market. The Company has developed a business model that combines the sale of energy commodities with value-added services offered to its customer community. Over recent years, UNION has progressively expanded its operating ecosystem through initiatives focused on energy efficiency, photovoltaic system development, and the sharing of renewable energy. At the same time, the Group has embarked on a vertical integration strategy across the energy value chain, strengthening its direct procurement activities and developing new business lines complementary to its traditional core operations.
Key Rating Assumptions
In 2025, UNION S.R.L. continued its growth trajectory, further expanding its customer base to approximately 57,600 active PODs and PDRs (+15.9% compared with 2024). The increase in the customer base translated into higher sales volumes, reaching approximately 123 GWh of electricity and more than 18 million Smc of natural gas. Growth in business volumes, the progressive consolidation of the direct procurement model on energy markets, and the contribution of complementary activities enabled the Company to maintain strong profitability levels. Despite a slight decline compared to the previous year, mainly attributable to higher write-downs on trade receivables, EBITDA stood at €9.25 million, while EBIT amounted to €9.04 million. Profitability remained well above sector median levels, as reflected by net profit of €5.90 million, an ROI of 22.0%, and an ROE of 42.9%.
From a financial and capital structure perspective, another year of strong operating performance further strengthened shareholders’ equity, which increased to €13.76 million. This development led to a marked improvement in solvency indicators, with the leverage ratio declining to 1.92x and financial leverage standing at 0.35x, confirming the limited reliance on financial debt. The Company also continues to benefit from a positive net cash position and a strong liquidity profile, both of which support a balanced financial structure and provide adequate resources to sustain the planned growth investments.
UNION S.R.L. has a straightforward ownership structure, with share capital equally divided between Emmanuelle Cilli and Sogen S.r.l., a company wholly controlled by Marco Tibaldo. The Company is managed by a Sole Director, while the statutory audit is carried out by an external auditor. Given the significant growth achieved in recent years and the prospects for further expansion, a gradual strengthening of the governance framework and control systems is expected, in line with the Company’s organizational development and the increasing need for management oversight. At the same time, the Company has undertaken a progressive group structuring process through the incorporation and acquisition of companies operating in areas complementary to its core business, including the initiatives related to the Union Park projects, as well as Union Smart S.r.l., Union Tech S.r.l., Union Real Estate S.r.l., Kairos S.r.l., and Empire S.r.l., supporting the Group’s strategy of vertical integration and business diversification.
Compared with its sector peer group, UNION demonstrates a satisfactory competitive position, supported by the growth in scale achieved over recent years. The Company exhibits solvency levels above the sector median and strong profitability, placing it among the best-performing operators within the reference sample. The sector continues to display adequate median solvency levels and a sound financial balance, while profitability, despite a decline in 2025, remains overall at satisfactory levels.
Between the end of 2025 and 2026, the energy and economic environment has been characterized by a high degree of uncertainty. At the global level, electricity demand continues to grow and renewable energy sources, particularly solar and wind power, are expanding further, while fossil fuels still maintain a central role in the energy mix. Geopolitical tensions in the Middle East, especially those related to Iran and the Strait of Hormuz, have increased volatility in oil and gas prices, generating inflationary pressures and influencing monetary policy decisions.
In Italy, despite the increase in renewable energy generation, the country's strong dependence on natural gas continues to support elevated energy prices, prompting the Government to postpone the closure of certain coal-fired power plants in order to safeguard security of supply.
From a macroeconomic perspective, Italian economic growth remained moderate in the first months of 2026, supported mainly by the services sector, while manufacturing has been affected by rising energy costs and weak external demand. Household consumption and investment have expanded only gradually due to persistent uncertainty and the erosion of purchasing power. According to the latest projections by the Bank of Italy, GDP is expected to grow by 0.5% in both 2026 and 2027, accelerating to 0.8% in 2028, although significant risks remain related to geopolitical developments and the evolution of energy markets.
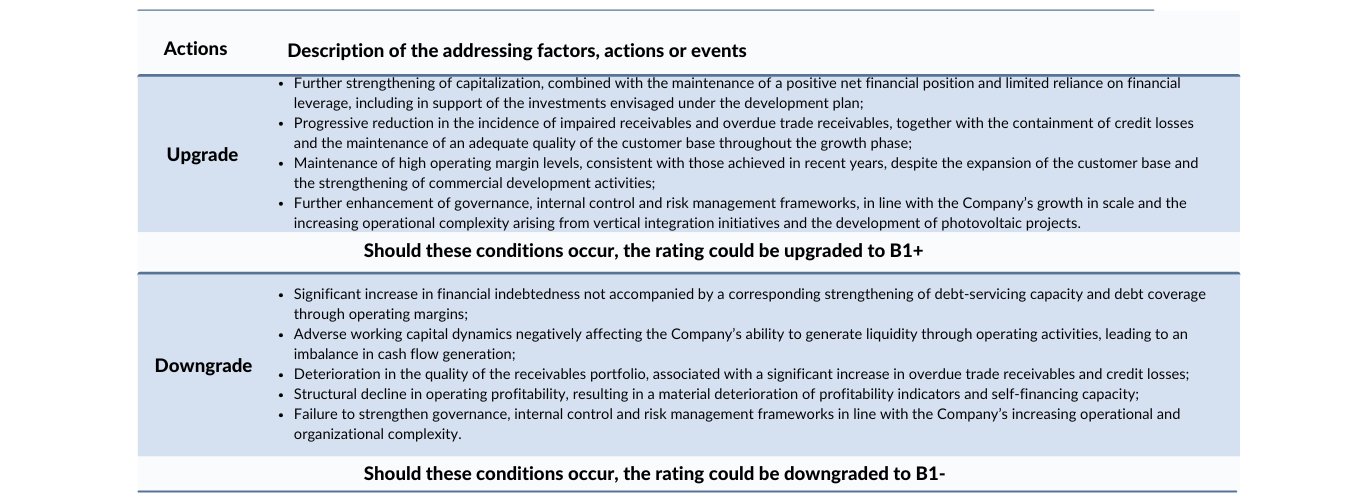
Sensitivity Analysis
In the following table, the addressing factors, actions or events that could lead to an upgrade or a downgrade are summarized:
Important
The present Corporate Credit rating is issued by modefinance under EU Regulation 1060/2009 and following amendments.
The present rating is solicited and is based on both private and public information. The rated entity and/or related third parties have provided all private information used. modefinance had access to some accounts and other relevant internal documents of the rated entity and/or related third parties. Solicited and unsolicited ratings issued by modefinance are of comparable quality, as the solicitation status has no effect on methodologies used. More comprehensive information on modefinance Corporate Credit Ratings are available at http://cra.modefinance.com/en
The present Corporate Credit Rating is issued on MORE Methodology 2.0 and Rating Methodology 1.0. A comprehensive description of both methodologies, as well as information on modefinance Rating Scale and Mappings, is available at http://cra.modefinance.com/en/methodologies.
For information on historical default rates of modefinance Corporate Credit Ratings please refer to ESMA Central Repository and ESMA European Rating Platform.
modefinance refers to default as a company under bankruptcy, or under liquidation status, or under administration or for which missed payments on a financial obligation are officially recorded.
The quality of the information available on the rated entity and used to determine the present rating was judged by modefinance as satisfactory.
Please note that modefinance does not perform any audit activity and is not in a position to guarantee the accuracy of any information used and/or reported in the present document. As such, modefinance can accept no liability whatsoever for actions taken based on any information that may subsequently prove to be incorrect.
The present credit rating was notified to the rated entity in order to identify potential factual errors, as prescribed by the CRA Regulation.
No amendments were applied after the notification process.
The rated company has not purchased ancillary services from modefinance.
The rating action issued by modefinance was performed independently. The analysts, members of the rating team involved in the process, modefinance Srl and its members and shareholders do not have any conflicts of interest in relation to the Rated Entity and/or Related Third Parties. If in the future a potential conflict of interest is identified in relation to the persons reported above, modefinance Ratings will provide the appropriate information and if necessary the rating will be withdrawn.
The present Credit Rating is an opinion of the general creditworthiness that modefinance issues on the rated entity, and should be relied upon to a limited degree. The issued rating is subject to an ongoing monitoring until withdrawal.
Contacts
Head Analyst - Stefano Chirsich, Rating Analyst
stefano.chirsich@modefinance.com
Responsible for Rating Approval - Giada D'Avenia, Rating Process Manager
giada.davenia@modefinance.com